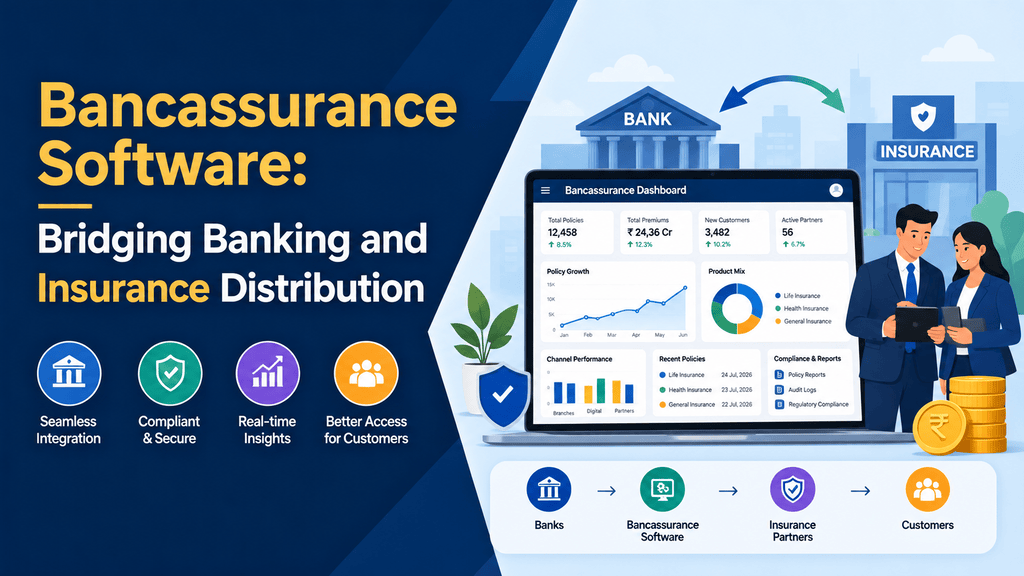
Bancassurance — the practice of banks distributing insurance products alongside their core banking services — has become one of the fastest-growing insurance distribution channels in India. For a bank, this isn’t a small side project. It means taking on an entirely new layer of operations on top of everyday banking: policy onboarding, renewals, relationship manager (RM) training, premium collection, and compliance reporting. Without the right technology backbone, this quickly turns into a manual, fragmented, and error-prone process — one that can end up costing more than it earns. This is exactly where dedicated Bancassurance Software makes the difference between a bancassurance channel that scales smoothly and one that becomes an operational headache.
Why Bancassurance Needs Purpose-Built Technology, Not Generic Tools
When a bank decides to distribute insurance, it is effectively running two businesses through one channel — banking and insurance — often with the same branch staff handling both. Many banks initially try to manage this with spreadsheets, manual registers, or insurance-company-provided tools that weren’t designed with a bank’s scale or workflow in mind. The result is usually duplicate data entry, delayed renewals, inconsistent reporting, and RMs who are undertrained on the insurance side of their job.
Winsoft’s insurance solutions are built specifically for the insurance distribution industry, using technology designed to automate the business processes of insurance distribution. That distinction matters: this isn’t insurance software repurposed for banks — it’s built around the reality that insurance distribution, at scale, needs its own dedicated back office, front office, and reporting layer, separate from (but connected to) a bank’s core banking systems.
Smart Insurance: The Operational Core of Bancassurance
At the center of a bank’s bancassurance operations sits SmartInsurance, a comprehensive solution for life and non-life insurance distribution. For a bank running high policy volumes across hundreds of branches, this translates into three practical capabilities:
- A seamless Back Office that manages the processing workload insurance distribution generates — policy issuance, renewals, endorsements, and the administrative volume that comes with selling insurance at branch scale.
- A user-friendly Front Office, which matters because the people actually selling these policies are bank staff, not insurance specialists. A system that’s intuitive enough for branch employees to use without extensive retraining is what keeps adoption high and errors low.
- An exhaustive reporting feature, because bancassurance brings its own compliance and audit requirements that sit alongside — but are distinct from — a bank’s existing regulatory reporting. Insurance regulators, product partners, and internal audit teams all need visibility into how policies are being sold and serviced, and manual reporting simply doesn’t hold up at scale.
Together, these three pieces mean a bank isn’t just “adding insurance products” to its counter — it’s running a properly managed second business line with the operational rigor that requires.
Solving the RM Training Bottleneck
One of the most underestimated challenges in bancassurance is people, not technology. Bank RMs are trained bankers — they aren’t insurance professionals by default, and turning them into competent insurance distributors takes structured onboarding and ongoing training. Do this manually, through classroom sessions and paper certification records, and it becomes one of the biggest bottlenecks to scaling a bancassurance channel across a large branch network.
Winsoft addresses this directly with AGENT, an Automated General & Life Insurance Training Tracker System built specifically for the insurance distribution industry. It empowers insurance distributors to onboard their RMs digitally — which means a bank can bring hundreds of RMs across multiple branches up to speed on insurance products and compliance requirements without building a manual training program from the ground up. For a bank with an expanding branch network, this digital onboarding capability is often what separates a bancassurance rollout that scales in months from one that takes years.
Managing the Full Policy Lifecycle, Not Just the Sale
Selling a policy is only the beginning. What happens after — renewals, premium collection, endorsements — is where most bancassurance operations lose efficiency if there’s no automation in place. This is where AGILE, Winsoft’s Automated General Insurance & Life Insurance Enrolment System, comes in. It covers the policy lifecycle from entering a new policy of the insured person to automating the yearly premium payment.
For a bank managing thousands of policies sold through its branches, this lifecycle automation is what keeps the bancassurance business profitable rather than becoming an administrative drain. Manual premium follow-ups and renewal tracking don’t scale — automated systems do, and they also reduce the compliance risk that comes with missed renewals or premium lapses.
Supporting Government Insurance Schemes Through Bank Branches
In India specifically, banks aren’t just distributing private insurance products — they’re often the primary channel through which government insurance schemes reach citizens, particularly in semi-urban and rural areas. Winsoft’s SmartPM Scheme is built for exactly this role. It’s a browser-based and mobile-responsive solution that offers Back Office, Front Office, and online APIs for processing the onboarding and renewal of customers under Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) and Pradhan Mantri Suraksha Bima Yojana (PMSBY).
This matters because government scheme distribution comes with its own operational patterns — high enrollment volumes, seasonal renewal cycles, and reporting requirements tied to government mandates — that differ from how a bank might sell a private life insurance policy. Having a system built specifically to handle PMJJBY and PMSBY onboarding through APIs means banks can plug this into their existing digital channels rather than running it as a separate manual process.
Bancassurance as Part of a Bigger Digital Banking Strategy
Bancassurance rarely happens in isolation. For most banks, introducing or scaling a bancassurance channel is one part of a much broader push toward operational modernization. Many banks that invest in bancassurance technology are doing so alongside wider Digital Transformation Services initiatives — modernizing multiple business lines, including insurance distribution, banking operations, and customer-facing digital channels, at the same time.
Scaling a new distribution channel like bancassurance also puts pressure on technical teams, particularly during implementation and integration phases. This is where banks often turn to IT Staff Augmentation — bringing in additional technical resources for the duration of a rollout without committing to long-term hiring, so the bancassurance implementation doesn’t stall waiting for internal bandwidth.
It’s also worth noting that this same underlying philosophy — giving a bank a dedicated, purpose-built platform for a secondary distribution business — applies beyond insurance. Winsoft’s Pension Distribution Solution follows the same principle for banks distributing National Pension System products, reinforcing a broader pattern: as banks take on more third-party financial products, each distribution line benefits from its own dedicated operational backbone rather than being forced into generic, one-size-fits-all systems.
Why This Matters for Banks Right Now
As competition among banks intensifies and interest income margins come under pressure, fee-based income from bancassurance has become an increasingly important revenue stream. But that revenue only materializes if the operational side — onboarding, training, policy servicing, renewals, and compliance reporting — can actually keep pace with sales ambitions. A bank that sells aggressively but services poorly ends up with high lapse rates, frustrated customers, and regulatory scrutiny, all of which erode the very revenue bancassurance was meant to generate.
Conclusion
Bancassurance offers banks a genuine, scalable growth opportunity — but only when the technology behind it can support the full lifecycle, from RM training to policy servicing to government scheme processing. Winsoft’s insurance distribution suite — SmartInsurance, AGENT, AGILE, and SmartPM Scheme — is built to handle exactly this, giving banks a single, automated foundation to run insurance distribution alongside their core banking business, without it becoming an operational burden.