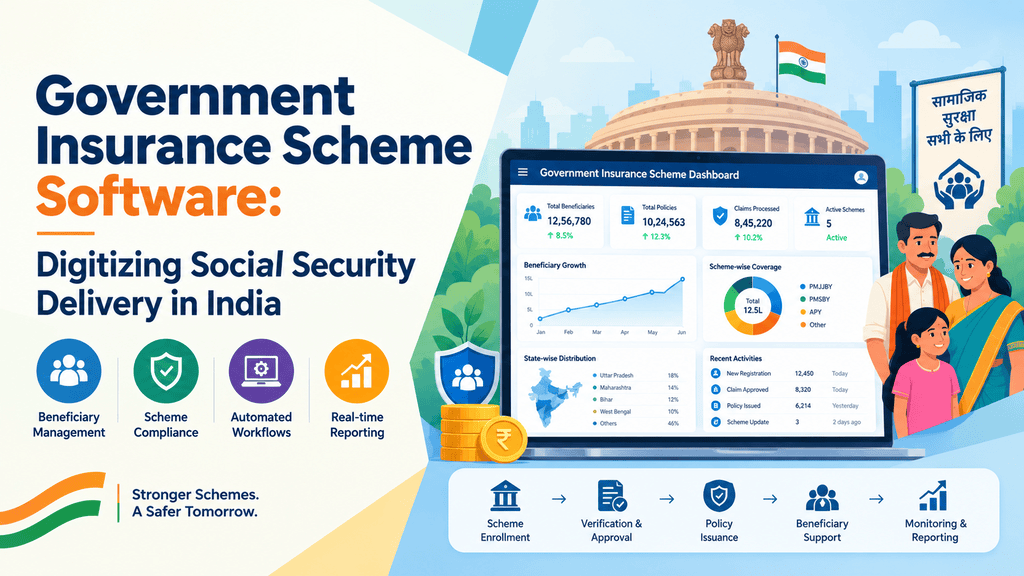
Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) and Pradhan Mantri Suraksha Bima Yojana (PMSBY) are two of India’s largest social security insurance schemes, designed to bring life and accident insurance coverage to millions of citizens who might otherwise remain uninsured. Banks and financial distributors are the primary channel through which these government schemes reach the public — which means the onboarding, renewal, and premium management for these schemes runs directly through bank branches and digital banking channels. Managing this at national scale, across recurring annual renewal cycles, is not something that works well with manual processes. This is exactly the gap that purpose-built Government Insurance Scheme Software is designed to close.
Why PMJJBY and PMSBY Need Dedicated Technology
PMJJBY is a government-backed life insurance scheme, while PMSBY is a government-backed accident insurance scheme — both offered to Indian citizens through participating banks. Winsoft’s SmartPM Scheme was built specifically to digitize this process. Notably, Winsoft’s Jan Suraksha Portal APIs are now live and available, reflecting direct integration with the government infrastructure these schemes run on.
The core purpose of the platform is straightforward: digitization of government-based insurance schemes to enable financial distributors to serve their clients efficiently, at the volume these national schemes demand. For a bank, this isn’t a one-time onboarding exercise — PMJJBY and PMSBY both require annual renewal, meaning the operational workload repeats every year for every enrolled customer, across potentially millions of policyholders nationally.
Understanding the PMJJBY Module
The PMJJBY module allows customers to onboard and auto-renew for the scheme, which — as a government-backed life insurance product — needs to work reliably at scale. Importantly, the system is flexible to integrate with any life insurance provider, meaning banks aren’t locked into a single insurer’s technical infrastructure to offer this scheme to their customers. This flexibility matters because different banks partner with different insurers for PMJJBY coverage, and a rigid, single-insurer system would limit which banks could realistically deploy the platform.
Understanding the PMSBY Module
Similarly, the PMSBY module allows customers to onboard and auto-renew the premium for the accident insurance scheme. Like its PMJJBY counterpart, this module is flexible to support any general insurance provider, giving banks the same freedom to work with their chosen insurance partner rather than being constrained by the software itself.
Together, these two modules mean a bank can offer both of India’s flagship social security insurance schemes through a single unified platform, rather than managing separate systems or manual processes for each.
How SmartPM Scheme Handles the Full Process
SmartPM Scheme is a comprehensive, browser-based and mobile-responsive solution offering Back Office, Front Office, and online APIs for processing the onboarding and renewal of customers under both PMJJBY and PMSBY. This three-part structure means the platform isn’t just a data-entry tool — it covers the complete operational chain from a customer walking into a branch (or applying digitally) to the scheme being processed on the back end and renewed automatically each year.
Core Processing Capabilities
At the heart of the platform, PMJJBY and PMSBY processing covers:
- Onboarding — enrolling new customers into the scheme
- Recurring premium — handling the annual premium cycle that both schemes require
- Account closure — managing exits from the scheme when needed
This covers the entire customer lifecycle within the scheme, not just the initial sign-up, which is critical given how much of the operational burden in government scheme distribution comes from ongoing renewal management rather than first-time enrollment.
Dashboard Visibility
A dashboard gives banks and distributors visibility into scheme performance and processing status — important when managing enrollment and renewal activity across potentially thousands of branches simultaneously.
Integration With Insurance Companies
The platform supports both file-based and API-based integration with insurance companies, giving banks flexibility depending on how their insurance partners are set up technically. This dual-integration approach means the platform can work with insurers who have modern API infrastructure as well as those still relying on file-based data exchange.
Premium Collection and Reversal
Initial premium collection is built into the platform, along with a reversal of premium amount in case of rejected requests — an important operational safeguard, since not every enrollment request will be successfully processed by the insurer, and customers need their premium refunded promptly when that happens.
Compliance and Control
Maker and Checker functionality, configurable as per each bank’s requirement, ensures the platform meets internal audit and control standards that banks operate under — a non-negotiable requirement for any system handling customer financial data and government scheme enrollment at scale.
Reporting
MIS reports provide the visibility banks and regulators need into scheme performance, enrollment numbers, and renewal rates — data that’s essential given the public accountability attached to government-backed insurance schemes.
API-First, Digitally Native Architecture
The platform offers consumable APIs for digital journeys and integrates with Core Banking systems via APIs, meaning PMJJBY and PMSBY enrollment can be embedded directly into a bank’s existing digital banking channels rather than existing as a separate, disconnected system. Winsoft describes the platform as easy and simple to use, yet flexible to integrate — a combination that matters given how varied core banking environments are across different banks.
Key Benefits for Banks and Distributors
Pulling these capabilities together, SmartPM Scheme delivers a set of practical benefits for banks managing government insurance scheme distribution:
- Mobile-responsive application, supporting access across devices
- Simplified onboarding journey, reducing friction for both customers and branch staff
- Automated renewal process, addressing the single biggest recurring operational burden in scheme management
- SMS and email alerts, keeping customers informed about enrollment status and renewal dates
- Attractive dashboard, giving stakeholders clear visibility into scheme performance
- Flexibility for customization, allowing the platform to adapt to a bank’s specific operational and insurer-partnership needs
Fitting Government Scheme Distribution Into a Bank’s Broader Strategy
Government insurance scheme distribution doesn’t operate as an isolated function — it’s typically one part of a bank’s broader financial inclusion and digital strategy. Banks investing in platforms like SmartPM Scheme are often doing so as part of wider Digital Transformation Services initiatives, modernizing customer onboarding, digital channels, and back-office operations across multiple product lines simultaneously — not just for PMJJBY and PMSBY, but as part of a connected digital banking ecosystem.
Because SmartPM Scheme integrates deeply with core banking systems and insurance company APIs, implementation and rollout often require additional technical capacity, particularly during integration and testing phases. This is where banks frequently rely on IT Staff Augmentation to bring in the technical resources needed without committing to long-term hires purely for a rollout period.
It’s also worth noting that government scheme distribution sits alongside Winsoft’s broader insurance distribution capabilities. Just as SmartPM Scheme handles PMJJBY and PMSBY specifically, Winsoft’s Insurance Distribution Software (SmartInsurance) handles the broader life and non-life insurance distribution a bank might offer alongside government schemes — meaning a bank’s insurance distribution technology strategy can cover both private and government-backed products through a connected suite rather than fragmented, standalone systems.
Conclusion
PMJJBY and PMSBY are national-scale social security schemes that depend on banks to reach citizens effectively — and that only works if the underlying technology can handle high-volume onboarding, automated annual renewals, and insurer integration without breaking down. SmartPM Scheme’s Back Office, Front Office, and API-driven architecture give banks a single, purpose-built platform to manage the complete lifecycle of both schemes — from first enrollment to automated renewal, premium reversal, and compliance reporting — turning what could be an overwhelming manual burden into a streamlined, auditable digital process.