Categories
Blog

Insurance Management Software: How It Simplifies Insurance Operations

Insurance distribution in India is growing fast, and not just in the metros. As banks, brokers, and intermediaries push deeper into semi-urban and rural markets, the volume of policies, insurer tie-ups, and compliance requirements they handle is growing right along with it. Somewhere in that growth, manual processes start breaking down.

This is exactly the gap Insurance Management Software is built to close. It gives insurance distributors and brokers one connected platform to manage advisors, operations, and customers, instead of juggling spreadsheets, phone calls, and disconnected insurer portals.

This blog looks at why manual processes fall short, what a proper insurance management platform actually does, and what distributors should check before adopting one.

Why Manual Insurance Distribution Operations Fall Short

Distributors and brokers who still rely on manual or semi-digital processes typically run into the same set of problems:

  • Proposal forms, premium collection, and renewal tracking scattered across registers or spreadsheets.
  • No single view of policies sold across multiple insurers.
  • Income and commission calculations done manually, with base, bonus, top-up, and clawback components easy to miscalculate.
  • Customers are restricted to branch visits or phone calls to buy or renew a policy.
  • Delayed or incomplete reporting when management or regulators ask for numbers.

None of these problems are unusual. They are simply what happens when a growing distribution business tries to run on tools that were never designed for the scale or complexity of multi-insurer, multi-channel insurance sales.

What Insurance Management Software Actually Does

At its core, a proper platform connects three groups that insurance distribution depends on: the people selling policies, the operations team running the business, and the customers buying and renewing cover.

For Advisors and Relationship Managers

Advisors get a workspace to fill proposal forms, collect premiums, track upcoming renewals, and manage auto-renewals and cancellations, with SMS and email notifications keeping both the advisor and the customer in the loop. This alone removes a large share of the manual follow-up that eats into an advisor’s selling time.

For the Operations Team

This is usually where the heaviest lifting happens. Operations teams get:

  • Master management to support products from multiple insurance companies across categories.
  • User management and access control, often integrated with existing identity systems.
  • Automated income calculation and reconciliation, covering base, bonus, top-up, clawback, and loyalty components.
  • An open, API-based framework to connect with different insurers for quotation, proposal, issuance, renewal, and servicing.
  • Support for digital payment modes, including core banking integration, payment gateways, and cards.

Because the income structure in insurance distribution is rarely a flat number, getting this calculation right, and being able to reconcile it against what insurers actually pay, matters more than most people outside operations realise.

For Customers

Policyholders increasingly expect to manage their own insurance. Insurance Management Software typically gives them a self-service portal to purchase or renew policies through net or mobile banking, supported by eKYC integration and payment gateway access, with a straightforward interface that does not require a branch visit for routine transactions.

For Reporting and Compliance

A dynamic reporting layer sits on top of all this, covering enrolment, issuance, policy enquiry, policy expiry, and renewal-due reports, along with a management dashboard for a real-time view of the business. This reporting also supports the audit and regulatory compliance checks that insurance distribution businesses are regularly subject to.

Capabilities Worth Looking For Beyond the Core Platform

A few additional capabilities are worth checking for, especially for banks and larger distributors. For institutions already investing in broader Digital Transformation Services, insurance operations are often one of several areas being modernised alongside core banking and payments, so a platform that fits naturally into that wider shift, rather than sitting apart from it, tends to hold up better over time. This becomes particularly relevant for banks running bancassurance operations, where insurance distribution needs to work alongside existing Banking Technology Solutions rather than as a disconnected add-on.

Digital certification tracking for sales teams, particularly relevant where relationship managers need periodic IRDA certification. A good system automates scheduling training, tracking exam status, and generating the required certification documents, right through to exit formalities when someone leaves the sales team.

Key Benefits at a Glance

  1. Accurate income tracking – base, bonus, top-up, clawback, and loyalty components calculated and reconciled automatically.
  2. Faster policy issuance and renewals – across web, mobile, branch, and advisor channels.
  3. Reduced dependency on insurers for data – distributors hold their own consolidated view of policies and customers.
  4. Audit-ready reporting – enrolment, issuance, expiry, and renewal-due reports generated without manual compilation.
  5. Better customer experience – self-service options backed by eKYC and digital payments

What to Look for Before Choosing a Platform

Before adopting a system, distributors and brokers should evaluate it against a few practical points:

  1. Multi-insurer, multi-product support, so the platform can accommodate existing and future tie-ups without rework.
  2. Accurate income calculation logic, capable of handling base, bonus, top-up, clawback, and loyalty components correctly.
  3. Built-in compliance and certification tracking, rather than compliance treated as a separate, manual process.
  4. Multi-channel customer access, including web, mobile, and branch, with digital payment support.
  5. Open API architecture, allowing integration with insurers as well as other internal systems used by the distribution business.

Getting clarity on these points before implementation helps avoid disruption later and ensures the platform genuinely fits how the distribution business operates.

Conclusion

Insurance distribution has moved well past the point where spreadsheets and manual follow-ups can keep pace. Between multiple insurer tie-ups, layered income structures, growing compliance requirements, and customers who want to transact on their own terms, distributors and brokers need a system built specifically for how their business works. Insurance Management Software brings advisors, operations, and customers onto one connected platform, and for distribution businesses aiming to grow without a proportional rise in manual effort, that shift is becoming less optional every year.

Frequently Asked Questions

1. Who is Insurance Management Software built for? 

It is built primarily for insurance distributors, brokers, and banks running bancassurance operations, covering their advisors, operations teams, and end customers, rather than for insurance companies managing underwriting.

2. Can it handle policies from more than one insurance company? 

Yes. These platforms typically use an open, API-based framework specifically so distributors can manage tie-ups with multiple insurers, across life, health, and general insurance, from a single system.

3. How does it help with income and commission accuracy? 

It automates calculation of components like base, bonus, top-up, clawback, and loyalty payouts, and reconciles them, reducing the manual errors that are common when this is tracked by hand across a large policy book.

4. Can customers renew or buy policies without visiting a branch? 

Yes. Most platforms include a customer-facing portal for purchasing or renewing policies through web or mobile channels, usually with eKYC and digital payment support built in.

5. Is this type of software only useful for large distribution businesses? 

No. Larger businesses benefit from handling higher policy volumes and bigger sales teams, but smaller distributors gain just as much from reduced manual effort in income calculation, renewal tracking, and reporting.
Categories
Blog

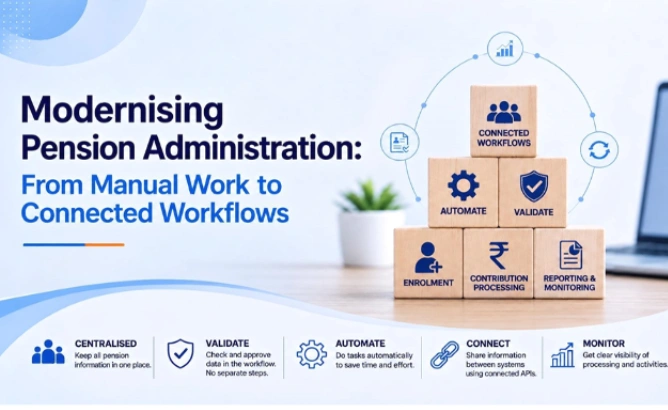
Modernising Pension Administration: From Manual Processing to Connected Workflows

Pension administration involves a series of connected operational activities, from enrolment and eligibility validation to contribution processing, transaction management and reporting. When these activities depend heavily on manual intervention or disconnected processes, organisations need a more structured way to manage the complete processing journey.

Where Pension Administration Becomes Challenging

Manual enrolment and processing

Pension enrolment can involve multiple registration and processing steps. When these activities are handled manually, operational teams may need to repeat the same tasks across different stages.

Eligibility validation

Eligibility information needs to be checked as part of the enrolment process. Managing these checks separately can add additional effort to the overall processing journey.

Contribution and SI processing

Recurring contributions and Standing Instructions (SI) require consistent processing. When these activities are managed manually, maintaining a connected workflow becomes more challenging.

Pension transaction management

Pension administration continues beyond enrolment. Related transactions need to be processed and managed efficiently while remaining connected to the overall pension journey.

The Impact of Manual Processing

When pension activities are managed through separate manual steps, teams can spend significant operational effort on data entry, validation and transaction handling.

The challenge is therefore not limited to one individual activity. The wider requirement is to bring connected pension processes together and reduce unnecessary manual intervention across the workflow.

How Technology Can Address These Requirements

A centralised approach brings related pension activities into one connected processing environment and supports automation across defined stages.

A Practical Example: Addressing a Pension Processing Challenge

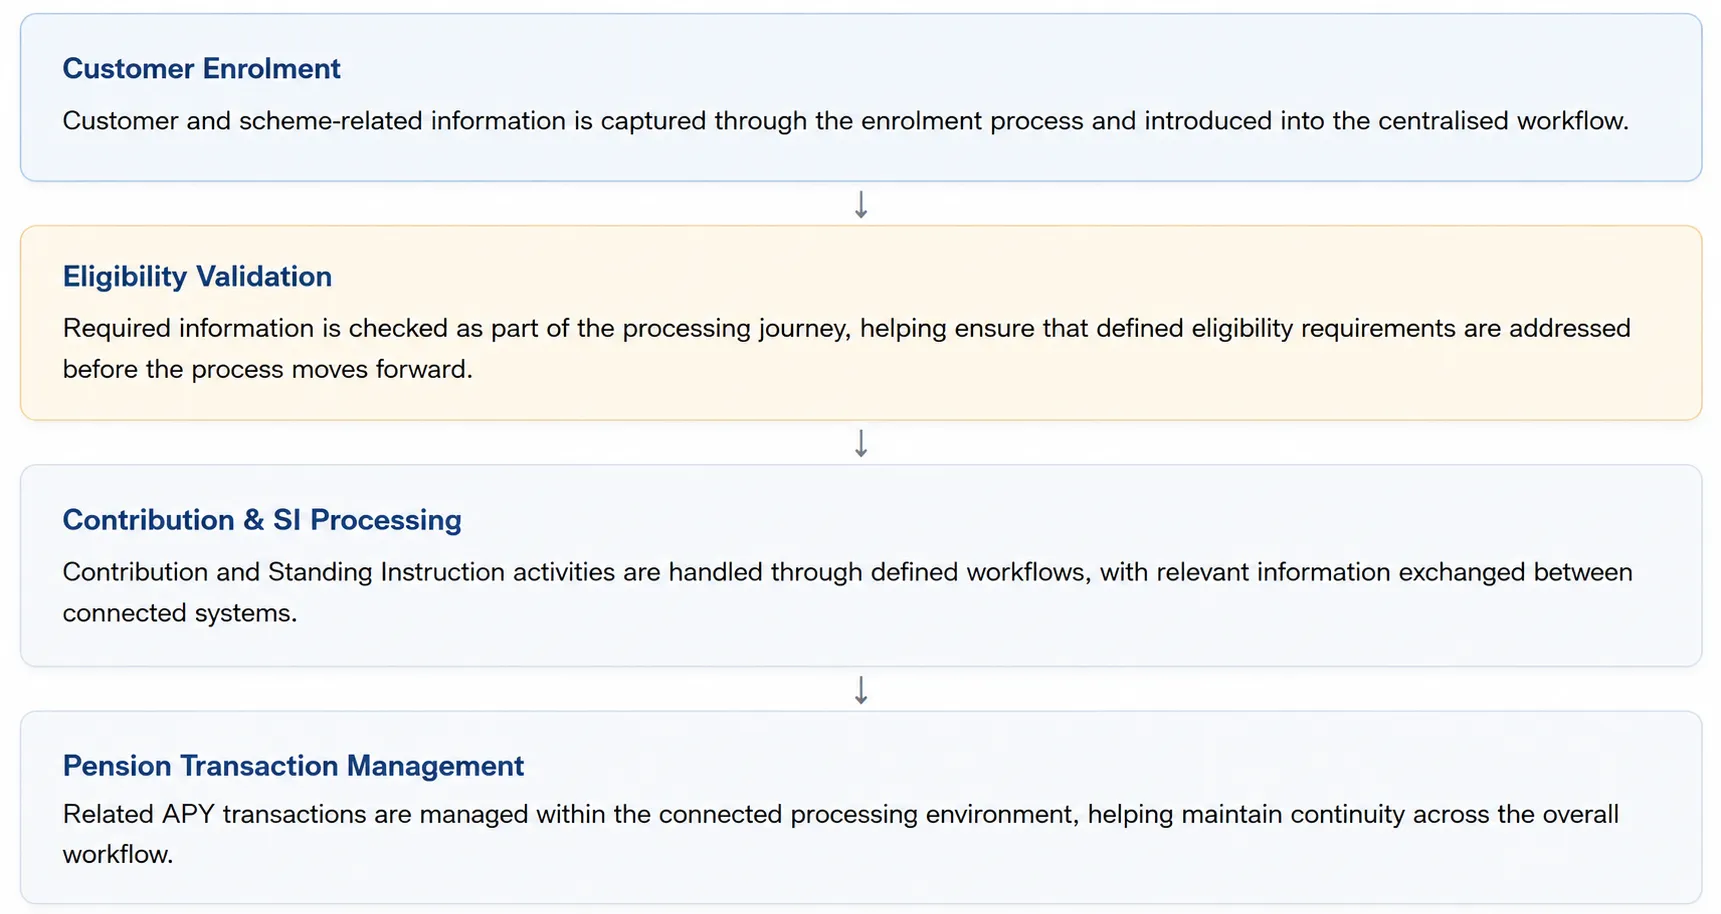
A bank approached Winsoft Technologies with a requirement to improve the processing of APY (Atal Pension Yojana, a pension scheme in India). The bank needed a more centralised way to manage customer enrolment, eligibility validation, contribution and Standing Instruction (SI) processing, and related pension transactions.

Although the requirement was specific to APY, the underlying challenge is common to pension administration: multiple processing activities and systems need to work together efficiently while reducing dependence on manual processing.

The Requirement

The requirement was to digitise the APY registration and processing activities, reducing reliance on manual work while bringing the relevant stages into a more connected processing environment.

This included customer registration and enrolment, eligibility validation, contribution and Standing Instruction (SI) processing, and related pension transactions. The aim was to improve coordination between the systems involved and create a more consistent digital workflow.

How Winsoft Addressed the Requirement

Winsoft Technologies addressed the requirement through SmartAPY, a browser-based solution supporting both Front Office and Back Office APY processing.

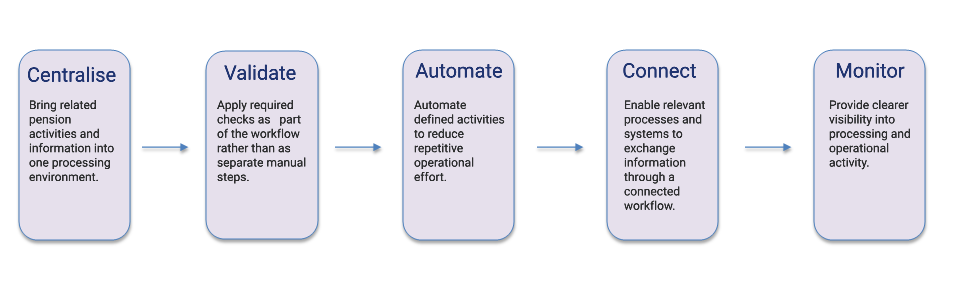
The solution brought the relevant processing activities together within a centralised workflow, while API-based connectivity enabled information to be exchanged between the relevant systems. This helped automate defined activities and reduce the need for repetitive manual intervention.

The APY processing journey can be represented as:

The APY processing journey image representation

By connecting these stages within a structured workflow, the approach supported a more consistent end-to-end processing journey.

The Outcome

The approach helped reduce manual intervention in APY registration and processing while bringing related activities into a more connected workflow. It also provided a more structured way to manage the processing journey across the relevant systems.

While the example is based on APY in India, the underlying approach is relevant to pension administrators and financial organisations in other markets facing similar challenges around manual processing, disconnected systems and workflow management.

Explore Smart APY

Beyond a Single Pension Scheme

The requirement demonstrated through APY reflects a broader need within pension administration.

Different pension schemes and products may operate under different rules, eligibility requirements and transaction processes. However, the underlying technology requirements can be similar: centralised processing, connected systems, workflow automation, validation and operational visibility.

A technology approach built around these requirements can therefore support organisations looking to modernise pension administration without being limited to one particular pension scheme.

Conclusion

Pension administration involves multiple activities that need to work together efficiently. When these activities depend heavily on manual intervention or disconnected processes, organisations can benefit from bringing them into a more structured and connected workflow.

The practical example demonstrates how a pension-processing requirement can be addressed by centralising activities, connecting systems through APIs and automating defined workflows. The same principles can be applied more broadly to organisations looking to improve the way they manage pension operations.

FAQs

Common challenges can include manual enrolment, eligibility validation, contribution processing, transaction management and the need to coordinate information across different systems.

A centralised workflow can automate defined activities and connect related processing stages, reducing repetitive manual intervention.

APIs can enable relevant systems to exchange information, helping connect different stages of a pension-processing workflow and reduce the need for separate manual data handling.

It brings related activities into a connected processing environment, helping organisations manage workflows more consistently while improving operational visibility.

Categories
Blog

Atal Pension Yojana Software: Simplifying Scheme Administration

Administering Atal Pension Yojana at a bank branch involves far more than collecting a monthly contribution. It means registering subscribers correctly, executing recurring debits without fail, staying compliant with PFRDA (Pension Fund Regulatory and Development Authority) and FATCA (Foreign Account Tax Compliance Act) regulations, and keeping subscriber records accurate for a scheme that can run for decades. Atal Pension Yojana Software exists to bring structure to this exact set of responsibilities.

This blog looks at what this kind of software actually covers, based on how it’s built to support banks administering APY at scale.

What Is Atal Pension Yojana Software?

At its core, this is a browser-based platform offering Back Office and Front Office processing of APY contributions, built specifically to help financial distributors serve their clients’ retirement needs under this government scheme. It’s designed around three practical goals: making subscription easy through auto-debit facilities, keeping the total cost of managing APY distribution low, and supporting subscribers whether they engage through a bank branch or online. It typically works alongside other retirement-focused tools, such as National Pension Scheme Software, within an institution’s broader Pension Management Software setup, though each is built around the specific rules of the scheme it serves.

Key Capabilities That Drive Day-to-Day Administration

Subscriber Registration and Recurring Debits

The software captures and processes APY registration requests along with the subsequent recurring debit of contributions, built to handle large subscriber volumes rather than one-off registrations. Standing instruction (SI) debit execution can run on either a FIFO basis or a lump sum basis, depending on what a client institution requires.

Digital Onboarding Through e-NPS and Aadhaar eKYC

Subscriptions can be accepted through the e-NPS platform using Aadhaar-based eKYC, reducing dependence on physical paperwork for onboarding. The platform also maintains a PRAN library and interfaces directly with NSDL for SRF, SCF, and SMF file generation, keeping subscriber records aligned with central systems.

Regulatory Compliance Built Into the System

APY administration carries specific regulatory obligations, and the software is built to support APY FATCA regulations alongside PFRDA compliance requirements, rather than leaving these checks to manual oversight.

Integration With Core Banking and Mobile Channels

The platform integrates with a bank’s core banking system through APIs, and also connects with internet banking through APY On Net application integration. A separate API is available for integration with a bank’s retail mobile application, extending APY access to whichever channel a subscriber prefers to use.

Operational Controls That Support Accuracy

Beyond the customer-facing side, the software includes a set of operational safeguards designed for the sensitivity of long-term pension administration:

  • Two-way security and data checks through a Maker/Checker workflow.
  • User-level access rights control.
  • A consolidated subscriber registration form with built-in data entry validations.
  • Auto allocation of PRAN following the initial contribution transaction.
  • SI execution for contribution charges and overdue interest.
  • Automatic SI closure once a subscriber reaches 60 years of age.
  • Integration with core banking for customer and account data, along with a fund transfer API.
  • NEFT support available directly through the branch module.

Reporting Built for Day-to-Day Administration

Branch and back-office staff rely on a specific set of reports to manage APY operations without needing to compile data manually:

  • Acknowledgement slip generation
  • SI registration report
  • SI due for the day
  • SI status report
  • Collection summary report
  • APY account status report

These reports give staff a clear, current picture of where each subscriber and each contribution cycle stands, without requiring manual cross-referencing across systems.

Supporting the Subscriber Relationship Over Time

APY isn’t a one-time transaction, it’s a relationship that can span decades, and the software is built with that timeline in mind. Subscribers receive customisable SMS and email alerts, and banks can modify subscriber details, personal information, nominee details, or pension plan specifics, as circumstances change over time.

The platform also supports pension upgrade or downgrade requests, APY closure, and spouse continuation, along with the ability to generate SRF, SMF, SCF, and DCF files for upload to the NSDL website when required. End-of-day and beginning-of-day processes handle SI execution and SRF/SCF file generation automatically, while overdue penalty calculation is built in rather than tracked manually.

Why Branch and Internet Channel Support Matters

APY’s subscriber base spans a wide range of banking preferences and access levels, some subscribers engage primarily through branch staff, while others are comfortable managing their subscription online. Supporting both branch and internet channels within the same platform means banks don’t need to maintain separate systems or processes depending on how a given subscriber chooses to interact, while still keeping every record centralised and consistent.

Conclusion

Administering Atal Pension Yojana accurately, across large subscriber volumes and long contribution timelines, depends heavily on the systems supporting it behind the scenes. Atal Pension Yojana Software built around registration accuracy, regulatory compliance, core banking integration, and clear reporting gives banks the operational foundation needed to manage this responsibility consistently. For institutions administering APY at scale, this level of structure isn’t just operationally convenient, it directly affects how reliably subscriber records and contributions are managed over the life of the scheme.

FAQs

1. What does Atal Pension Yojana software actually manage?

It handles subscriber registration, recurring contribution debits, PRAN allocation, regulatory compliance, and reporting, covering both Back Office and Front Office processing.

2. How are subscribers onboarded digitally?

Subscriptions can be accepted through the e-NPS platform using Aadhaar-based eKYC, alongside a consolidated registration form with built-in validations.

3. Does the software support both branch and online engagement?

Yes, it supports both branch-based processing and internet banking integration through APY On Net, along with API support for retail mobile applications.

4. What happens when a subscriber turns 60?

The system automatically closes the subscriber’s standing instruction at age 60, reducing the need for manual tracking of maturity dates.

5. Can subscriber details be updated after registration?

Yes, the platform supports modification of personal, nominee, and pension details, along with pension upgrade or downgrade requests, closure, and spouse continuation.

Categories
Blog

Mutual Fund Software: Simplifying Fund Distribution for Banks and Distributors

Mutual fund distribution has grown considerably more complex over the past decade. Investors expect faster onboarding, banks and distributors are managing larger client bases, and reconciling revenue against registrar data has become a persistent operational challenge. Managing all of this manually, through paperwork and spreadsheets, is no longer realistic at scale.

This blog looks at how Mutual Fund Software is helping banks and distributors simplify fund distribution, and what capabilities actually make a meaningful difference in day-to-day operations.

Why Fund Distribution Has Outgrown Manual Processes

For years, mutual fund distribution relied heavily on paper-based onboarding, manual transaction tracking, and periodic reconciliation against registrar and transfer agent (RTA) data. This worked reasonably well at smaller volumes.

As distribution businesses have scaled, a few recurring challenges have become harder to ignore:

  • Onboarding new investors takes longer than it should due to paper-heavy processes.
  • Reconciling income and commission data against RTA records is time-consuming and error-prone.
  • Advisors and relationship managers often lack real-time visibility into client portfolios.
  • Revenue leakage from unnoticed reconciliation errors can go undetected for months.

These aren’t isolated inconveniences, they compound as transaction volumes grow, eventually reaching a point where manual processes simply can’t keep pace.

What Does Mutual Fund Software Actually Cover?

At its core, this software digitises the operational backbone of mutual fund distribution through three connected portals: a customer-facing portal, an advisor/RM portal, and an operations portal, each supporting a different part of the distribution workflow, alongside business-wide MIS reporting.

The Customer Portal

This is where investors interact directly with their portfolio. Capabilities here typically include instant digital onboarding with eKYC and risk profiling, a comprehensive portfolio dashboard, digital goal planning and tracking, and instant execution of both lumpsum and systematic transactions. Investors also get performance analytics and alerts, support for non-financial transactions, responsive design for handheld devices, call centre-assisted transactions, and a cart facility for managing multiple fund selections at once.

The Advisor/RM Portal

Relationship managers work from a dedicated dashboard offering a comprehensive view of customer portfolios with analytics, along with RM-specific reports. This portal supports RM-assisted onboarding, re-risk profiling, and transaction execution, as well as scheduling of reports and alerts. It also includes prospect and campaign management, along with tools for tracking RM targets and incentives.

The Operations Portal

This is where the heavier back-office work happens: integration with data service providers and existing core systems, rule-based revenue calculation covering upfront, annualised, trail, incentive, and claw-back structures, and automated revenue reconciliation. It also handles seamless order processing through RTA and BSE Star interfacing, customer portfolio returns calculation, RTA reverse feeds for transactions, NAV, and income data, along with customisable reporting and integration with document management systems.

Business MIS

At a business level, reporting covers assets under management, mobilisation, income, active systematic investment plans, and both year-to-date and month-to-date performance, including zone-wise business breakdowns.

Why Does This Matter for Both Banks and Distributors?

A fair question is whether banks and independent distributors have fundamentally different needs when it comes to this kind of software.

In practice, both face similar operational pressures, they need to onboard investors efficiently, serve clients across multiple channels, and reconcile revenue accurately. What differs is scale and structure. Banks often manage mutual fund distribution as one line of business among several, sitting alongside offerings like insurance, where Bancassurance Software handles a similarly structured, multi-partner distribution model, requiring seamless integration with core banking and third-party systems. Independent distributors, by contrast, may rely on the mutual fund platform as their primary operational backbone. Software designed to serve mid and large distributors, as well as banks and financial institutions, needs to accommodate both scenarios without forcing either into an ill-fitting structure.

How Does This Reduce Operational Strain?

When onboarding, reporting, and reconciliation are automated rather than manual, the impact extends beyond time savings. Staff who previously spent significant time on paperwork and manual cross-checking can redirect that time toward client engagement and business development. Relationship managers walk into client conversations with current portfolio data rather than outdated reports, supported by RM target and incentive tracking that keeps performance visible. And discrepancies in revenue calculation, across upfront, trail, incentive, or claw-back structures, get flagged early through automated reconciliation, rather than discovered much later during an audit.

This shift, from reactive problem-solving to proactive, automated processing, is often what separates distribution businesses that scale smoothly from those that struggle under their own growth. For institutions implementing or scaling this kind of system, IT Staff Augmentation offers a practical way to bring in the specific technical expertise needed during setup or expansion, without adding long-term headcount for a need that may be temporary.

Conclusion

Fund distribution for banks and distributors has moved well beyond what manual processes can reasonably support. Mutual Fund Software built around digital onboarding, multi-portal engagement across customers, advisors, and operations, automated revenue reconciliation, and structured business reporting forms the operational foundation modern distribution businesses need. For banks and distributors looking to reduce administrative strain while improving accuracy and client experience, this kind of purpose-built platform isn’t simply a convenience, it’s increasingly the standard for how fund distribution gets done efficiently at scale.

FAQs

1. What is mutual fund software used for?

It digitises mutual fund distribution operations through connected customer, advisor, and operations portals, covering onboarding, transaction execution, revenue reconciliation, and reporting.

2. Is this software suitable for both banks and independent distributors?

Yes, it’s typically built to serve mid and large distributors as well as banks and financial institutions, with integration support for core banking and third-party systems.

3. How does this software help with revenue accuracy?

It applies rule-based revenue calculation across upfront, annualised, trail, incentive, and claw-back structures, with automated reconciliation against RTA data to catch discrepancies early.

4. What can investors do through the customer portal?

Investors can complete digital onboarding with eKYC, track goals, execute lumpsum and systematic transactions, view portfolio analytics, and manage selections through a cart facility.

5. How does this software support relationship managers specifically?

RMs get a dedicated dashboard with portfolio analytics, RM-assisted onboarding and transaction tools, prospect and campaign management, and tracking for their own targets and incentives.

Categories
Blog

Why Manual Commission Reconciliation Is Costing Insurers More Than They Think

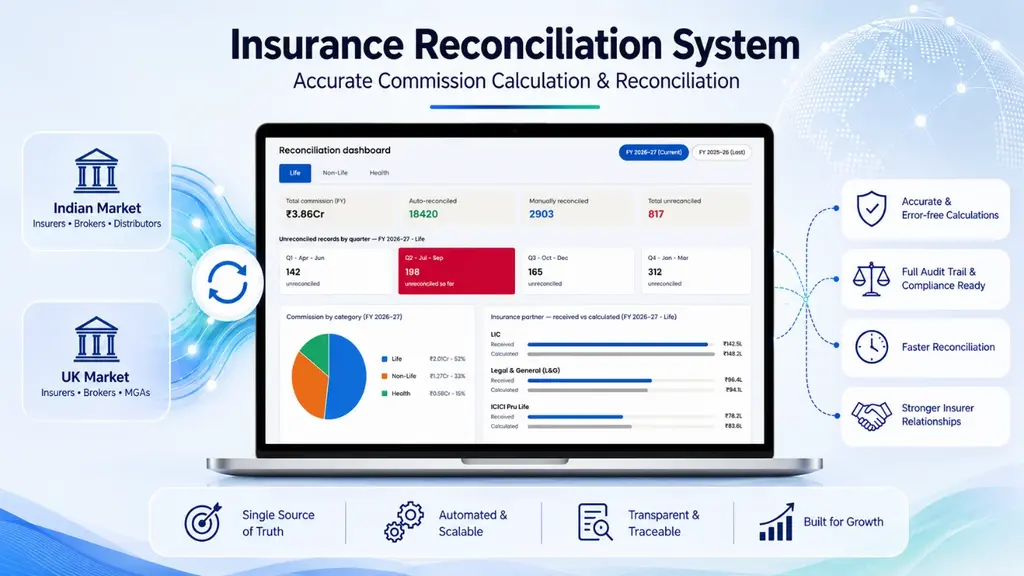
As insurance businesses expand across multiple insurers, product lines, brokers, and financial intermediaries, calculating and reconciling commissions grows more complex than spreadsheets and disconnected systems can handle. Every mistyped entry and every “we’ll check it later” mismatch carries a cost — in staff hours, compliance exposure, and strained insurer relationships. The Insurance Reconciliation System, built by Winsoft Technologies, removes that cost by automating commission calculation, data validation, and reconciliation on a single platform.

Where Commission Reconciliation Breaks Down

Fragmented, inconsistent data. Insurer details, product structures, and commission rates are often maintained separately across teams, with no single source of truth — so every calculation inherits that inconsistency.

Manual, error-prone processing. Large volumes of policy and transaction data are entered by hand, introducing errors that often go unnoticed until they’re far harder to fix.

Unverifiable figures. Commission calculated in spreadsheets typically lacks an audit trail, making discrepancies hard to trace — or to trust.

Lack of accountability. Without a structured review process, there’s often no record of who entered or approved master data — a liability during compliance reviews.

The result: finance and operations teams spend more time reconciling than analysing, while the organization carries ongoing compliance risk.

Is Manual Reconciliation Itself the Error?

Mismatches aren’t usually caused by a single mistake — they’re caused by the process used to catch them. When reconciliation depends on someone manually comparing spreadsheets line by line across thousands of policies, error isn’t the exception; it’s the expected outcome.

Manual reconciliation fails quietly. A missed row or an outdated rate doesn’t announce itself — it sits in the data until an audit or a revenue gap forces someone to go looking. By then, fixing it costs far more than preventing it would have.

The goal isn’t to make people more careful. It’s to remove manual matching from the process entirely.

How the Insurance Reconciliation System Closes the Gap

What’s needed is a single, centralized system that maintains accurate master data at the source, processes high transaction volumes reliably, calculates commission systematically, and reconciles it against insurer-reported figures automatically — with full traceability at every step. This is the Insurance Reconciliation System Winsoft Technologies has built. Every problem named above has a corresponding answer built into it.

Centralised masters solve fragmented data

The Insurance Reconciliation System maintains a single source of truth for insurer details, product and business-class hierarchies, premium frequencies, policy status codes, and payment methods — along with rate masters for Normal, Clawback, and Loyalty Commission, and an Event Master tracking lifecycle changes like In-Force, Lapsed, Cancelled, and Matured. When this data lives in one place, every downstream calculation inherits consistency.

Structured bulk uploads solve manual processing

Instead of hand entry, transaction volumes move through structured file uploads — similar in purpose to a Commission / Business Statement (often called a bordereaux), the standard submission format between brokers, MGAs, and insurers. Policy data, status, premium transactions, and payouts all follow the same validation logic: files are checked for quality, valid and invalid records are separated automatically, and a summary shows exactly what needs correction.

Maker-Checker solves unverifiable figures

No single person can create and finalise a record alone. The Insurance Reconciliation System applies a Maker-Checker model — the Four Eyes Principle, a dual control standard widely used across regulated financial services in India, the UK, and other markets. One user submits a record; another reviews and authorises or rejects it before it goes live.

Automated reconciliation solves undetected mismatches

Commission is calculated for a selected insurer and date range directly from validated transaction data, with exceptions flagged automatically. An automated reconciliation engine then compares calculated commission against what was actually received, sorting every record as Matched, Received but Not Calculated, Calculated but Not Received, or Partial Match. Nothing is left to chance discovery.

Full reporting solves lack of accountability

A detailed Reconciliation Report, exportable by class of business, insurer, and date range, shows exactly where every policy stands — premium amounts, received vs. calculated commission, policy status, and branch details. Combined with the maker-checker trail, this gives compliance and audit teams a clear, traceable record of who did what, and when.

Insurance Reconciliation System — Advantages That Solve the Problem

Problem How the Insurance Reconciliation System Solves It
Fragmented, inconsistent data Centralised masters give every team the same source of truth
Manual, error-prone processing Structured bulk uploads with automatic validation replace manual entry
Unverifiable commission figures Maker-Checker dual control verifies every record before it goes live
Undetected mismatches Automated reconciliation surfaces every mismatch
Lack of accountability A full audit trail supports compliance and audit readiness

The outcome: faster settlements, fewer errors, stronger audit readiness, and more transparent relationships with insurers — at a scale spreadsheets can’t sustain.

Conclusion

Commission calculation and reconciliation sit at the heart of the relationship between insurers and their distribution partners — getting it wrong, or too slowly, costs trust and efficiency. Winsoft Technologies’ Insurance Reconciliation System solves this with centralised master management, automated calculation, built-in reconciliation, and maker-checker controls — part of Winsoft’s broader work in Insurance Distribution Software and Digital Transformation in the BFSI Sector.

FAQs

A dual control mechanism where one user creates a record and another reviews and authorises it before it goes live — a standard control in regulated financial services, including India and the UK.

Commission is calculated per insurer and date range from uploaded transaction data using predefined rate cards. Records that can't be processed cleanly are flagged for review.

It compares calculated commission against commission received and classifies each record as Matched, Received but Not Calculated, Calculated but Not Received, or Partial Match.

A detailed, exportable view of every policy's reconciliation status — premium amounts, commission rates, received vs. calculated figures, and branch details.

Categories
Blog

How BFSI Solutions Help Banks Reduce Operational Costs

Operational costs quietly eat into a bank’s profitability in ways that don’t always show up in a single line item. Manual processes, redundant paperwork, delayed reconciliations, and inefficient staffing models all add up over time. For banks operating in a competitive, tightly regulated environment, finding ways to reduce these costs without compromising service quality has become a genuine priority.

This blog looks at how the right technology and workforce solutions are helping banks bring operational costs down, practically and sustainably.

Where Do Operational Costs Actually Come From?

Before looking at solutions, it helps to understand where the biggest cost drains typically sit within a bank’s operations:

  • Manual data entry and repetitive back-office tasks
  • Reconciliation errors that require rework and correction
  • Underutilised or overstaffed teams during low-demand periods
  • Legacy systems requiring ongoing maintenance and manual workarounds
  • Compliance processes that rely heavily on manual documentation
  • Customer service inefficiencies leading to higher resolution times

Each of these, on its own, might seem manageable. Together, across a large banking operation, they represent a substantial and recurring cost burden.

How Do BFSI Solutions Address This?

Rather than applying generic business software to banking-specific problems, the technology platforms and service models grouped under BFSI Solutions in India are shaped around the operational realities banks actually face, including regulatory requirements, transaction volumes, and multi-stakeholder coordination.

1. Automation Reduces Repetitive Manual Work

A large share of a bank’s operational cost comes from tasks that don’t require judgment, just accuracy and consistency. Automating processes like data validation, document verification, and routine reconciliation frees up staff time for higher-value work while reducing the error-driven rework that manual processes often create.

2. Centralised Systems Cut Down Redundancy

When different departments operate on disconnected systems, the same data often gets entered or verified multiple times. Centralised platforms eliminate this redundancy, allowing information to flow across departments without repeated manual handling.

3. Better Compliance Reduces Costly Penalties

Non-compliance isn’t just a regulatory risk, it’s a direct financial one. Automated compliance tracking and audit trails reduce the likelihood of penalties while also cutting down the staff hours spent on manual compliance checks.

4. Scalable Systems Avoid Overstaffing

Traditional operations often require adding staff to handle volume spikes, then carrying that cost even during quieter periods. Digital platforms that scale processing capacity up or down based on demand help banks avoid this cost inefficiency.

Is Automation Alone Enough to Cut Costs Significantly?

This is a fair question, since technology alone doesn’t solve everything. Automation certainly reduces the cost of repetitive tasks, but banks still need skilled people to manage, maintain, and improve these systems over time. This is where workforce strategy becomes just as important as the technology itself.

Rethinking Workforce Costs Through Flexible Staffing

Hiring full-time, permanent staff for every technical requirement isn’t always the most cost-efficient approach, particularly for specialised skills needed only during specific project phases or peak periods.

Staff Augmentation Services allow banks to bring in skilled technology professionals on a flexible, as-needed basis, whether for system implementation, ongoing support, or scaling up during high-demand periods like IPO seasons or regulatory deadline crunches. This model reduces the long-term overhead associated with expanding permanent headcount, while still giving banks access to the expertise they need, when they need it.

Where This Model Typically Helps Most

  • Short-term technology implementation projects
  • Peak-period operational support
  • Specialised skill requirements that don’t justify full-time hires
  • Testing and quality assurance during system upgrades

By treating workforce needs as flexible rather than fixed, banks can align staffing costs much more closely with actual demand.

A Closer Look: Cost Reduction in Specific Banking Functions

Mutual Fund Distribution

Banks offering mutual fund distribution services often deal with high transaction volumes, complex commission structures, and frequent reconciliation requirements. Mutual Fund Software for Banks automates much of this back-office complexity, reducing the manual effort and associated staffing costs that come with manually tracking transactions, commissions, and NAV updates across multiple fund houses.

IPO and Capital Markets Processing

During IPO periods, application volumes can spike dramatically within short windows. Automated processing systems help banks handle this surge without the need for significant temporary staffing increases, keeping costs controlled even during high-pressure periods.

Insurance Distribution

Banks distributing insurance products benefit from automated commission tracking and compliance management, reducing the administrative overhead typically associated with managing multiple insurance partnerships manually.

Regional Considerations: Why Local Context Matters

Cost-efficiency strategies aren’t always uniform across regions. Banks looking for BFSI Solutions Mumbai often deal with high transaction density and a concentration of institutional clients, requiring systems built to handle significant volume without performance bottlenecks. Meanwhile, banks seeking BFSI Solutions Pune may prioritise solutions that support growing retail banking networks and expanding semi-urban customer bases.

Understanding these regional operational patterns helps banks choose solutions genuinely suited to their specific branch networks and customer demographics, rather than adopting a one-size-fits-all approach.

Measuring the Actual Cost Impact

To understand whether these solutions are genuinely reducing costs, banks should track metrics such as:

  • Reduction in manual processing hours per transaction type
  • Decrease in reconciliation errors and associated rework
  • Staffing cost trends relative to transaction volume growth
  • Compliance-related penalty or remediation costs over time
  • Turnaround time improvements across key operational processes

Tracking these consistently over time gives a much clearer picture of cost impact than looking at technology spend alone.

Common Pitfalls to Avoid

Even well-intentioned cost-reduction initiatives can fall short if certain factors are overlooked:

  • Underestimating implementation time, which can delay expected savings
  • Insufficient staff training, leading to underutilisation of new systems
  • Choosing generic solutions not tailored to banking-specific requirements
  • Ignoring integration needs with existing core banking systems

Avoiding these pitfalls generally comes down to careful planning and choosing solutions built specifically for the complexities of banking operations.

Conclusion

Reducing operational costs in banking isn’t about cutting corners, it’s about eliminating inefficiency wherever it exists, whether that’s in repetitive manual processes, rigid staffing models, or fragmented systems. By combining the right technology with flexible workforce strategies, banks can bring costs down meaningfully while maintaining, and often improving, the quality of service they deliver to customers.

FAQs

Q1. How do BFSI solutions specifically help reduce operational costs for banks?

They automate repetitive manual processes, centralise fragmented systems, improve compliance accuracy, and allow staffing to scale flexibly with actual demand, all of which reduce unnecessary operational spending.

Q2. Is staff augmentation more cost-effective than hiring full-time employees?

For specialised or short-term technology needs, it often is, since it avoids the long-term overhead of permanent hires while still providing access to skilled expertise when required.

Q3. Which banking functions typically see the most cost savings from automation?

Functions with high transaction volumes and complex reconciliation needs, such as mutual fund distribution, IPO processing, and insurance commission tracking, tend to see significant cost benefits from automation.

Q4. Do regional differences affect which BFSI solutions a bank should choose?

Yes, transaction volumes, customer demographics, and branch network patterns can vary significantly by region, making it important to choose solutions suited to local operational realities.

Q5. What’s the biggest mistake banks make when trying to reduce operational costs through technology?

Choosing generic, non-specialised solutions or underestimating the time and training needed for proper implementation are among the most common pitfalls that delay expected cost savings.

Categories
Blog

How IPO Application Software Simplifies the IPO Journey

Anyone who has applied for shares in a public offering knows the drill: fill in details, block funds, wait, check status, hope for allotment. What most applicants don’t see is the sheer operational machinery working behind the scenes to make that simple-looking process happen accurately and on time. For banks, registrars, and financial institutions, that machinery increasingly runs on dedicated software built specifically for this purpose.

Let’s look at how this software actually simplifies the IPO journey, both for the institutions managing it and the investors applying through it.

The IPO Journey, From an Investor’s Perspective

To understand why this software matters, it helps to first walk through what an investor experiences when applying for an IPO:

  • Submitting an application with bid details through a bank or broker
  • Having the bid amount blocked in their account
  • Waiting through the subscription period
  • Checking allotment status once the process closes
  • Receiving shares (if allotted) or having blocked funds released

On the surface, this looks straightforward. But each of these steps involves coordination between multiple systems and parties, and any delay or error at any point directly affects the investor’s experience.

What Happens Behind the Scenes?

Here’s where it gets more complex. Behind each investor application, institutions need to:

  • Validate application details against regulatory requirements
  • Block and later release funds accurately, often across thousands of accounts simultaneously
  • Coordinate with registrars and depositories for share allotment
  • Generate reports for regulatory bodies and stakeholders
  • Handle investor queries and status updates at scale

During peak subscription periods, application volumes can spike dramatically within a short window, and manual processes simply cannot handle this kind of surge reliably.

What Is IPO Application Software?

IPO Application Software is built specifically to manage this high-volume, time-sensitive workflow. It automates the collection, validation, and processing of investor applications, while coordinating fund blocking, allotment, and refund processes across the institutions involved.

Rather than treating each application as a manual entry requiring individual attention, the software processes large volumes systematically, applying consistent rules and checks across every submission.

Core Functions It Typically Handles

  • Application Capture and Validation – The software captures investor details, bid quantities, and price information, checking for completeness and accuracy before processing continues.
  • Fund Blocking Coordination – Working closely with banking systems, it manages the blocking of application amounts in investor accounts, ensuring funds are available and correctly earmarked.
  • Bid Modification and Cancellation – Investors often need to modify or cancel bids during the subscription window. The software handles these changes while maintaining an accurate, updated record.
  • Allotment Processing Support – Once the subscription period closes, the software supports the allotment process by providing clean, validated application data to registrars.
  • Refund and Unblocking Management – For applications that don’t receive full allotment, the software coordinates the release of blocked funds accurately and promptly.

Why Does Speed Matter So Much Here?

IPO subscription windows are typically short, often just a few days, and application volumes tend to concentrate heavily toward the closing hours. A question worth asking is: What actually happens when application volumes surge unexpectedly?

Without automated systems, this surge can overwhelm manual processing capacity, leading to delays, errors, or even application rejections due to processing bottlenecks. Automated software is built to handle these volume spikes consistently, processing applications in real time regardless of how concentrated the submission pattern becomes.

Benefits for Different Stakeholders

For Banks

Banks benefit from reduced manual workload, fewer processing errors, and the ability to handle significantly higher application volumes without proportionally increasing staff involvement.

For Registrars

Registrars receive cleaner, pre-validated data, which simplifies the allotment process and reduces the back-and-forth typically needed to resolve application discrepancies.

For Investors

Investors experience faster confirmation, more accurate fund blocking and release, and clearer visibility into their application status throughout the process.

For Regulators

Regulatory bodies benefit from improved transparency and more reliable audit trails, both of which support better oversight of the public offering process.

How Does This Fit Into a Bank’s Broader Technology Ecosystem?

IPO application software rarely operates in isolation. For banks specifically, it needs to integrate closely with core banking systems, customer databases, and payment infrastructure. This is where the connection to broader Banking Technology Solutions becomes important, ensuring that IPO-specific processes work seamlessly alongside a bank’s existing digital infrastructure rather than functioning as a disconnected add-on.

This integration also matters for scalability. As banks handle multiple IPOs across a financial year, sometimes overlapping, having systems that work well together reduces operational friction considerably.

Connecting With the Wider Financial Software Ecosystem

Beyond banking integration, IPO application software also typically connects with depositories, clearing corporations, and other Financial Software Solutions involved in the capital markets ecosystem. This interconnected approach ensures that data flows accurately between all parties involved in an IPO, from the initial application to final share credit in an investor’s demat account.

Common Challenges Institutions Should Anticipate

Even with capable software in place, institutions should be prepared for certain recurring challenges:

  • Peak-hour traffic management during the final hours of subscription windows
  • Data reconciliation across multiple systems and stakeholders
  • Handling application errors gracefully without disrupting the broader process
  • Staying updated with evolving regulatory requirements around IPO processing

Planning for these challenges in advance, rather than reacting to them during a live IPO, tends to make a significant difference in how smoothly the process runs.

What Should Institutions Consider When Evaluating Software?

Since IPO application software plays such a critical role during high-stakes periods, evaluation should be thorough. Key considerations include:

  • How well does the system handle peak-volume traffic without slowdowns?
  • What level of integration does it offer with existing banking and depository systems?
  • How robust are its validation and error-handling capabilities?
  • What reporting and compliance features does it provide?
  • How reliable is vendor support during live IPO periods?

Given how time-sensitive IPO processing is, reliability under pressure often matters just as much as day-to-day functionality.

Conclusion

The IPO journey may look simple from an investor’s screen, but the operational reality behind it is considerably more complex. Dedicated application software brings structure, speed, and accuracy to this process, benefiting banks, registrars, regulators, and investors alike. As IPO activity continues to grow and application volumes climb, having reliable, well-integrated software in place isn’t just a convenience, it’s what allows the entire process to function smoothly under real-time pressure.

FAQs

Q1. What is IPO application software used for?

It automates the capture, validation, and processing of investor applications during a public offering, including fund blocking, bid modifications, and refund coordination.

Q2. Why is speed so important in IPO application processing?

Subscription windows are short, and application volumes often surge near the closing period, making automated, real-time processing essential to avoid delays or errors.

Q3. How does this software help banks specifically?

It reduces manual workload, minimises processing errors, and allows banks to handle high application volumes efficiently, particularly during peak subscription periods.

Q4. Does IPO application software work independently, or does it need to integrate with other systems?

It typically needs close integration with banking systems, depositories, and registrars to ensure smooth, accurate data flow throughout the IPO process.

Q5. What should institutions prioritise when choosing this kind of software?

Reliability under high traffic, strong integration capabilities, robust validation features, and dependable support during live IPO periods are all important factors.

Categories
Blog

Why Businesses Need Digital Transformation Services in the BFSI Sector

Ask any banking or financial services leader what keeps them up at night, and “staying relevant” will likely top the list. Customer expectations have shifted dramatically, regulatory requirements keep evolving, and legacy systems that once worked fine are now struggling to keep pace. The BFSI sector, perhaps more than any other, finds itself at a crossroads where digital adoption isn’t optional anymore — it’s foundational to survival.

This blog unpacks why that shift matters, what it actually involves, and how businesses across banking, insurance, and financial services can approach it practically.

The Pressure Points Driving Change

Before looking at solutions, it’s worth understanding what’s actually pushing BFSI businesses toward digital adoption in the first place.

  • Rising customer expectations. Today’s customers, whether retail investors or corporate clients, expect instant access, real-time updates, and self-service options. A process that takes days through manual channels feels unacceptable when everything else in their life happens at the tap of a screen.
  • Regulatory complexity. Compliance requirements in BFSI change frequently and carry serious consequences for non-compliance. Manual tracking simply cannot keep up with the pace and precision regulators now expect.
  • Operational inefficiency. Legacy systems, often built on outdated architecture, create bottlenecks. Data sits in silos, reconciliation takes longer than it should, and scaling operations becomes a resource-heavy exercise rather than a smooth process.
  • Competitive pressure. As more players, including newer, digitally native entrants, raise the bar on service delivery, traditional institutions face growing pressure to modernise or risk losing relevance.

What Do Digital Transformation Services Actually Cover?

The term gets used loosely, so it helps to define it clearly. Digital Transformation Services typically involve reimagining how a business operates, using technology to streamline processes, improve customer experience, and enable data-driven decision-making, rather than simply digitising existing paper-based workflows.

For BFSI specifically, this can include:

  • Modernising legacy core systems
  • Automating manual, repetitive back-office processes
  • Building customer-facing digital platforms and self-service portals
  • Integrating data across departments for unified visibility
  • Strengthening cybersecurity and compliance infrastructure
  • Enabling cloud adoption for scalability and cost efficiency

The scope is broad, which is exactly why a structured, phased approach tends to work better than attempting everything at once.

Is Digital Transformation Really Necessary, or Just a Trend?

This is a fair question, and one many decision-makers genuinely wrestle with. Isn’t this just another buzzword that will fade?

The honest answer is that while the terminology may evolve, the underlying shift is structural, not cyclical. Customer behaviour has permanently changed. Regulatory bodies increasingly expect digital-first compliance mechanisms. And operational costs of maintaining outdated systems only grow over time, both in direct expense and in opportunity cost from slower processes.

Businesses that treat this as optional often find themselves playing catch-up later, at a higher cost and with greater disruption than a planned, gradual transformation would have required.

Key Benefits for BFSI Businesses

1. Improved Customer Experience

Digital platforms allow customers to complete transactions, track applications, and access information without depending on branch visits or lengthy call centre interactions. This convenience directly influences customer satisfaction and retention.

2. Faster, More Accurate Operations

Automation reduces the time spent on repetitive manual tasks, from document verification to reconciliation, while also lowering the risk of human error in high-stakes financial processes.

3. Stronger Compliance Posture

Automated compliance tracking and audit trails make it considerably easier for institutions to stay aligned with regulatory requirements, reducing both risk and administrative burden.

4. Better Data-Driven Decisions

When data flows freely across departments instead of sitting in isolated systems, leadership gains clearer visibility into performance, risk, and opportunity, enabling faster, more informed decisions.

5. Scalability Without Proportional Cost

Digital infrastructure, particularly cloud-based systems, allows businesses to scale operations up or down based on demand without the heavy fixed costs associated with traditional infrastructure expansion.

How Does This Play Out in Specific BFSI Functions?

Banking Operations

From account opening to loan processing, digitisation significantly reduces turnaround times while improving accuracy and customer transparency throughout each stage.

Insurance Distribution

Digital platforms streamline policy issuance, claims processing, and commission management, particularly valuable given how many stakeholders are typically involved in insurance distribution chains.

Capital Markets and Public Offerings

Processes like IPO applications, historically paperwork-heavy and time-sensitive, benefit enormously from automation. IPO Management Software, for instance, allows institutions to handle high volumes of applications, allotments, and compliance checks with far greater speed and accuracy than manual methods ever could.

Wealth and Asset Management

Portfolio tracking, reporting, and client communication all become more efficient when built on integrated digital platforms rather than fragmented manual processes.

The India Context: Why It Matters Here Specifically

India’s BFSI sector operates under a unique combination of factors: a rapidly growing digital-first customer base, an evolving regulatory environment, and increasing financial inclusion initiatives extending services to previously underserved populations. This creates both significant opportunity and real complexity.

Businesses looking for BFSI Solutions in India need platforms and services that understand these local nuances, from regulatory frameworks specific to Indian financial markets to the operational realities of serving a diverse, geographically spread customer base across urban and semi-urban regions. Generic global solutions don’t always translate well without this contextual understanding.

Common Challenges in the Transformation Journey

Even well-planned digital transformation efforts run into obstacles:

  1. Legacy system integration can be technically complex and time-consuming.
  2. Change management across large employee bases requires sustained effort.
  3. Data migration demands careful planning to avoid errors or loss.
  4. Budget constraints can limit the pace or scope of transformation initiatives.
  5. Skill gaps internally may require external expertise to bridge them effectively.

Recognising these challenges early, and planning around them, tends to make the difference between a transformation effort that stalls and one that delivers sustained results.

A Practical Approach: Where Should Businesses Start?

Rather than attempting a complete overhaul immediately, many successful transformations follow a phased approach:

  • Start with a clear assessment of current pain points and priorities.
  • Identify quick wins that demonstrate value early, building internal buy-in.
  • Gradually modernise core systems, rather than a single disruptive migration.
  • Continuously gather feedback from both customers and internal teams.
  • Build in flexibility to adapt as technology and regulations evolve.

This measured approach reduces risk while still moving the organisation meaningfully forward.

Conclusion

Digital transformation in BFSI isn’t about chasing the latest technology trend, it’s about building the operational foundation needed to meet rising customer expectations, navigate regulatory complexity, and compete effectively in an increasingly digital-first market. Businesses that approach this thoughtfully, with clear priorities and realistic timelines, position themselves not just to keep pace with change, but to genuinely benefit from it over the long term.

FAQs

1. Why is digital transformation particularly important for BFSI businesses?

The sector faces unique pressures from regulatory complexity, rising customer expectations, and competitive dynamics, making digital adoption essential rather than optional for long-term relevance.

2. Does digital transformation mean replacing all legacy systems at once?

Not necessarily. Most successful transformations follow a phased approach, gradually modernising systems rather than attempting a complete overhaul simultaneously.

3. How does digital transformation help with regulatory compliance?

Automated tracking, audit trails, and standardised processes make it easier for institutions to stay aligned with evolving regulatory requirements while reducing manual compliance burden.

4. What role does automation play in areas like IPO processing?

Automation significantly speeds up high-volume, time-sensitive processes like IPO applications and allotments, while reducing the risk of manual errors during peak periods.

5. What should BFSI businesses look for in a transformation partner?

Understanding of local regulatory context, proven experience in financial services, scalable technology solutions, and a phased implementation approach are all important considerations.

Categories
Blog

National Pension System Software: Complete Guide

Retirement planning in India has changed significantly over the past two decades, and much of that shift can be traced back to the introduction of the National Pension System. What started as a scheme primarily for government employees has grown into a widely adopted retirement savings option across sectors. Behind this growth, however, sits a fairly intricate operational structure, one that depends heavily on the technology systems managing it.

This guide breaks down what National Pension System software actually does, why it matters, and what banks, financial institutions, and intermediaries should know about it.

Understanding the National Pension System First

Before getting into the software itself, it helps to first understand the retirement scheme it is designed to support. The National Pension System is a voluntary, defined-contribution retirement scheme where subscribers contribute regularly during their working years, with the accumulated corpus available upon retirement, subject to withdrawal rules.

Managing this at scale involves multiple parties:

  • Points of Presence (banks and financial institutions that onboard subscribers)
  • Central Recordkeeping Agencies that maintain subscriber records
  • Pension fund managers who invest contributions
  • Regulatory bodies overseeing compliance
  • Subscribers themselves, who need visibility into their accounts

Coordinating between all these parties manually would be extremely difficult, which is exactly why dedicated software has become essential.

What Does National Pension System Software Actually Do?

National Pension System Software is designed to handle the operational backbone of NPS administration. It typically covers subscriber onboarding, contribution processing, account tracking, and reporting, all in compliance with regulatory guidelines set for the scheme.

For institutions acting as Points of Presence, this software becomes the primary interface through which they manage day-to-day NPS-related activities on behalf of their customers.

Key Functions Covered by the Software

Subscriber Onboarding and KYC
Digital onboarding processes, including document verification and KYC checks, allow new subscribers to be registered quickly and accurately.

Contribution Management
The software tracks regular and one-time contributions, ensuring they’re correctly allocated to the subscriber’s account and reported to the relevant recordkeeping agency.

Account Statement Generation
Subscribers need periodic visibility into their contributions and corpus growth. Automated statement generation reduces the manual reporting burden on institutions.

Withdrawal and Exit Processing
Handling partial withdrawals, exits, and annuity purchase processes requires careful adherence to regulatory rules, which the software helps enforce consistently.

Compliance and Audit Trail
Given the regulated nature of pension products, maintaining a clear, timely audit trail is a core requirement that good software addresses by design.

How Is This Different From General Pension Management Software?

A fair question at this point is whether NPS-specific software is really necessary, or whether broader pension tools can do the job just as well.

Generally, Pension Management Software covers a wider range of retirement and pension products, including employer-sponsored pension schemes, gratuity management, and other retirement benefit structures. National Pension System software, by contrast, is built specifically around the operational and regulatory requirements unique to NPS, such as its specific contribution limits, tax treatment, and withdrawal rules. Institutions dealing primarily with NPS often find that purpose-built software offers more precise handling of these scheme-specific nuances than a generalised pension platform.

That said, many institutions offering multiple retirement products do look for platforms that can handle both, provided the NPS-specific rules aren’t compromised in the process.

Why Accuracy Matters So Much in NPS Administration

Because NPS involves long-term contributions that directly affect a subscriber’s retirement corpus, even small errors can have outsized consequences over time. A miscalculated contribution or a delayed update to a subscriber’s record isn’t just an administrative inconvenience, it can affect the subscriber’s actual retirement savings.

This is why institutions place such heavy emphasis on:

  • Accurate, real-time contribution tracking
  • Timely reconciliation with recordkeeping agencies
  • Clear audit trails for every transaction
  • Reliable subscriber communication and statement delivery
  • Strong data security given the sensitivity of financial and personal information

What About Atal Pension Yojana?

The Atal Pension Yojana is a related but distinct scheme, focused primarily on providing guaranteed pension income to workers in the unorganised sector. While it shares some administrative similarities with NPS, such as subscriber onboarding and contribution tracking, it operates under its own set of rules regarding contribution amounts, age eligibility, and pension payout structures.

Because of these differences, institutions handling both schemes often rely on Atal Pension Yojana Software alongside their NPS systems to ensure that each scheme’s specific requirements are managed correctly, rather than trying to force both into a single generic framework.

Common Challenges Institutions Face

Even with good software in place, institutions administering NPS often encounter a few recurring challenges:

  • Data reconciliation delays between the institution and central recordkeeping agencies
  • Subscriber grievance handling, particularly around contribution mismatches
  • Keeping pace with regulatory updates, which can affect contribution limits or withdrawal rules
  • Ensuring smooth digital onboarding for subscribers with limited digital literacy, particularly in semi-urban and rural areas

Addressing these challenges usually comes down to a combination of well-designed software and clear internal processes for handling exceptions.

What Should Institutions Look For in NPS Software?

When evaluating a platform, a few practical considerations tend to matter most:

  • How well does it integrate with central recordkeeping systems?
  • Does it support both digital and assisted onboarding processes?
  • How robust is its compliance and reporting functionality?
  • Can it scale as subscriber numbers grow over time?
  • What level of support is available for regulatory updates and system changes?

Working through these questions carefully before implementation tends to save institutions considerable operational friction later on.

Conclusion

As retirement planning continues to gain importance among Indian households, the systems supporting schemes like NPS need to be accurate, compliant, and easy for both institutions and subscribers to use. National Pension System Software plays a central role in making this possible, handling everything from onboarding to withdrawal processing with the precision that long-term retirement savings genuinely require. For institutions involved in pension administration, choosing the right technology isn’t just an operational decision, it directly affects the trust subscribers place in their retirement planning journey. 

FAQs

1. What is National Pension System software used for?

It manages the operational aspects of NPS administration, including subscriber onboarding, contribution tracking, account statements, and withdrawal processing.

2. Who typically uses this kind of software?

Points of Presence(POPs) such as banks and financial institutions, along with central recordkeeping agencies, use it to manage NPS-related activities.

3. Is National Pension System software different from general pension management tools?

Yes, it’s built specifically around NPS rules and requirements, while general pension management software often covers a broader range of retirement products.

4. How does this software help with compliance?

It maintains detailed audit trails and enforces scheme-specific rules around contributions and withdrawals, helping institutions stay compliant with regulatory requirements.

5. Can the same platform handle both NPS and Atal Pension Yojana?

Some platforms do support both, but given the distinct rules governing each scheme, institutions often use dedicated modules or software for each to ensure accurate handling.

Categories
Blog

Insurance Distribution Software For Banks And Insurance Companies

Insurance distribution today rarely runs through a single process. Government-backed schemes, private life and non-life products, sales force onboarding, and policy renewals all need to be managed simultaneously, often across hundreds of branches and thousands of relationship managers. Behind this everyday complexity sits a layer of software most customers never see, but one that determines how smoothly the entire distribution chain actually works.

This blog looks at what insurance distribution software typically covers, based on how these platforms are actually built and used across banks and financial distributors.

Why Insurance Distribution Needs Dedicated Software

Distributing insurance, particularly at scale, involves several distinct processes running in parallel:

  • Onboarding customers for government-backed insurance schemes
  • Managing life and non-life policy distribution through back-office processing
  • Training relationship managers before they can sell insurance products
  • Enrolling new policies and automating recurring premium payments

Handling each of these manually, across a large branch network, creates significant room for delays, inconsistent processes, and compliance gaps. Purpose-built software exists specifically to bring structure to this complexity.

Supporting Government-Backed Insurance Schemes

A meaningful part of insurance distribution in India today involves government social security schemes, such as those offering affordable life and accident insurance to underserved populations. Software built for this purpose typically includes:

  • A browser-based, mobile-responsive interface
  • A Back Office for internal processing
  • A Front Office for customer-facing onboarding
  • Online APIs to support digital enrolment and renewal

This kind of setup allows banks to onboard and renew customers under these schemes efficiently, without relying on manual, paper-based registration at the branch level.

Why Does This Matter for Financial Inclusion?

A fair question here is why banks would need dedicated software just for government scheme distribution, rather than folding it into general insurance processes.

The answer lies in scale and reach. These schemes are often aimed at large, geographically spread populations, many of whom may have limited prior exposure to formal insurance products. Dedicated digital onboarding and renewal processes make it possible to serve this scale efficiently, while keeping the process simple enough for both customers and branch staff to use confidently.

Life and Non-Life Insurance Distribution

Beyond government schemes, banks and distributors also handle a broader range of life and non-life insurance products. Insurance Distribution Software built for this purpose typically provides:

  • A seamless Back Office for managing overall processing
  • A user-friendly Front Office for customer and advisor interactions
  • An exhaustive reporting feature to track distribution performance

This combination allows distributors to manage day-to-day policy distribution activity while maintaining visibility into how the business is performing across products and channels.

Training the Sales Force

Insurance distribution isn’t just about the customer-facing process, it also depends heavily on properly trained relationship managers. Given regulatory expectations around who can sell insurance products, software designed for this purpose focuses specifically on:

  • Digitally onboarding relationship managers into the training process
  • Tracking training completion and status
  • Reducing the administrative burden of managing this manually across branches

For banks with large distribution networks, digitising this process significantly reduces the coordination effort required to keep sales staff trained and ready before they begin selling.

Policy Enrolment and Premium Automation

The final piece of the distribution chain involves the ongoing lifecycle of a policy once it’s sold. This includes:

  • Entering new policies for insured customers
  • Automating yearly premium payment processing

Automating this stage reduces the manual follow-up typically required to ensure premiums are paid on time, helping distributors maintain consistent policy servicing without constant manual tracking.

A Question Worth Asking: How Does This Fit Into a Bank’s Broader Systems?

A practical question for any bank evaluating this kind of software is how it fits alongside everything else already running internally. Since insurance distribution activity, onboarding, renewals, and premium processing ultimately touches customer accounts and payment flows, it’s worth considering how closely a platform can work with a bank’s existing Banking Technology Solutions, rather than functioning as a completely disconnected system. This is a factor banks may want to evaluate directly with any vendor, since the level of integration can vary.

What Should Banks and Distributors Look for in a Platform?

When evaluating options across these different functions, insurance schemes, general life and non-life distribution, RM training, and policy servicing, a few practical questions help guide the decision:

  • Does it support both government scheme distribution and broader life/non-life products?
  • How well does it handle relationship manager onboarding and training tracking?
  • Does it automate recurring processes like premium payments?
  • What level of reporting visibility does it offer across the distribution chain?
  • How well can it integrate with a bank’s existing customer and account systems?

Working through these questions helps ensure the chosen platform genuinely covers the full scope of a distributor’s insurance operations, rather than addressing only one part of it.

Conclusion

Insurance distribution involves considerably more than a single sales transaction. From onboarding customers into government-backed schemes to managing life and non-life policy distribution, training relationship managers, and automating premium payments, each stage benefits from dedicated digital processes. For banks and distributors managing this at scale, software built specifically around these functions helps keep operations consistent and considerably easier to manage across large branch networks.

FAQs

Q1. What does insurance distribution software typically cover?

It typically covers government scheme onboarding and renewal, life and non-life policy distribution processing, relationship manager training, and policy enrolment with premium automation.

Q2. Why is government scheme distribution handled separately from general insurance products?

These schemes are often aimed at large, underserved populations, so dedicated digital onboarding and renewal processes help distributors manage this scale efficiently.

Q3. How does this software help with relationship manager training?

It supports digital onboarding into the training process, helping banks track training completion and status before staff begin selling insurance products.

Q4. Does this kind of software automate premium payments?

Yes, it typically supports automation of yearly premium payment processing as part of the broader policy servicing process.

Q5. Does insurance distribution software need to integrate with a bank’s other systems?

Since it touches customer accounts and payment processes, integration with a bank’s existing systems is an important factor to evaluate when choosing a platform.

© 2026 Winsoft Technologies India Pvt. Ltd.