Categories
Blog

Insurance Distribution Software: Expanding Reach for Agents and Brokers

Insurance distribution in India runs through a vast, fragmented network of agents, brokers, and relationship managers — each responsible for onboarding customers, processing policies, tracking renewals, and staying compliant with reporting requirements. The bigger an insurer or distributor’s agent network grows, the harder it becomes to manage consistently without the right technology. Manual processes that work fine for a handful of agents start breaking down entirely once a distributor is managing hundreds or thousands of them across multiple branches and regions. This is precisely the operational challenge that purpose-built Insurance Distribution Software is designed to solve.

The Core Challenge: Scaling an Agent and Broker Network

Winsoft provides insurance software solutions to the insurance distribution industry using cutting-edge software technologies, with a specific focus on automating the business processes of the insurance distribution industry. That framing matters — expanding reach for agents and brokers isn’t just about recruiting more people into the network; it’s about giving them the tools to onboard, sell, and service policies efficiently once they’re in it. A distribution network that grows in headcount but not in operational capacity doesn’t actually expand reach — it just multiplies the manual workload.

SmartInsurance: The Foundation for Agent and Broker Distribution

At the core of expanding distribution reach is SmartInsurance, which provides a comprehensive solution for life and non-life insurance distribution. For agents and brokers operating across a network, this means:

  • A seamless Back Office that manages the processing workload generated as the agent and broker network grows — without this centralized processing capability, scaling the number of agents simply scales the administrative bottleneck
  • A user-friendly Front Office, which is critical for agent adoption. Agents and brokers vary widely in technical comfort, and a system that’s genuinely easy to use is what determines whether a distribution network actually adopts digital tools or reverts to manual workarounds
  • An exhaustive reporting feature, giving distributors and insurers visibility into how the agent and broker network is performing — which policies are being sold, by whom, and how efficiently

This combination is what allows a distribution network to expand its agent base without each new agent becoming an additional operational burden on the central office.

Solving the Agent Onboarding Bottleneck

One of the biggest constraints on expanding reach through agents and brokers is onboarding itself. Every new agent needs training, certification tracking, and a structured process to become productive — and doing this manually doesn’t scale past a certain network size. Winsoft addresses this directly with AGENT, an Automated General & Life Insurance Training Tracker System built specifically for the insurance distribution industry. It empowers insurance distributors to onboard their RMs digitally.

For a distributor trying to expand its agent and broker network quickly — whether entering new regions or scaling within existing ones — digital onboarding is often the deciding factor in how fast that expansion can actually happen. A manual, paper-based onboarding process caps how many new agents can realistically be brought on and trained in a given period. A digital tracking system removes that ceiling.

Managing the Policy Lifecycle at Scale

Onboarding agents is only the first step — once they’re active, the distribution network needs to actually process policies efficiently, from first sale through to annual renewal. This is where AGILE, Winsoft’s Automated General Insurance & Life Insurance Enrolment System, comes in. It enables the insurance business to run efficiently by providing an enrolment system from entering a new policy of the insured person to automating the yearly premium payment.

For agents and brokers, this matters directly — a distribution network’s reach isn’t just measured by how many policies get sold, but by how well those policies get serviced afterward. An agent network that generates high sales volume but can’t keep up with renewal processing and premium collection ends up with high lapse rates, which undermines the value of expanding the network in the first place. AGILE’s end-to-end enrollment-to-premium-automation approach is what keeps a growing agent network sustainable rather than just busy.

Extending Reach Into Government Insurance Schemes

Expanding distribution reach in India also increasingly means reaching customers through government-backed insurance schemes, which agents and brokers are often positioned to distribute alongside private products. Winsoft’s SmartPM Scheme is a comprehensive, browser-based and mobile-responsive solution offering Back Office, Front Office, and online APIs for processing the onboarding and renewal of customers under Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) and Pradhan Mantri Suraksha Bima Yojana (PMSBY), developed specifically to support the PM schemes offered to Indian citizens.

For agents and brokers looking to expand their reach into underserved or price-sensitive segments, government schemes represent a meaningful growth channel — but only if the technology behind them supports the same volume and renewal-tracking rigor as private insurance distribution. SmartPM Scheme extends the same operational discipline — back office processing, front-office usability, and API-driven onboarding — to this government scheme segment specifically.

Why the Front Office/Back Office Split Matters for Distribution Reach

A pattern worth noting across Winsoft’s insurance suite is the consistent separation between Back Office and Front Office capabilities, present in both SmartInsurance and SmartPM Scheme. This isn’t incidental — it reflects how insurance distribution actually works at scale. Agents and brokers need a front-office experience simple enough to use in the field or at a customer’s counter, while the organization behind them needs a back office robust enough to process, reconcile, and report on that activity centrally. Software that collapses this distinction, or handles only one side well, tends to either overwhelm agents with complexity or leave the central office without the processing power to support a growing network.

What Expanding Reach Actually Requires

Pulling this together, expanding distribution reach for agents and brokers depends on more than just recruiting — it requires technology that supports the network at every stage:

  1. Fast, digital onboarding for new agents and RMs (via AGENT), removing the training bottleneck that limits how quickly a network can grow
  2. Efficient policy processing, from enrollment through to annual premium automation (via AGILE), so growth in agent numbers doesn’t translate into a growth in unprocessed backlog
  3. A distribution platform built for both life and non-life products (via SmartInsurance), giving agents a single system to work across product lines rather than juggling separate tools
  4. Coverage of government scheme distribution (via SmartPM Scheme), extending reach into a segment agents increasingly need to serve
  5. Reporting depth that gives distributors visibility into how the expanded network is actually performing, not just how large it has become

Fitting Distribution Expansion Into a Broader Technology Strategy

Expanding an agent and broker network rarely happens as a standalone initiative — it’s usually part of a distributor’s wider push toward operational modernization. Many insurance distributors scaling their agent networks are doing so alongside broader Digital Transformation Services initiatives, modernizing not just insurance distribution but customer onboarding, digital channels, and back-office operations together.

Scaling a distribution network also puts real pressure on technical teams during implementation — particularly when integrating onboarding systems, policy processing, and reporting across a growing agent base. This is where distributors often rely on IT Staff Augmentation, bringing in additional technical resources for the rollout period without committing to long-term hires purely to support an expansion phase.

It’s also worth noting that this same principle of purpose-built, distribution-specific software extends across Winsoft’s broader suite. Just as SmartInsurance and AGENT are built specifically for insurance distribution, Winsoft’s Mutual Fund Software (SmartMutual) follows the same approach for mutual fund distributors — reinforcing a consistent pattern where each distribution business gets a dedicated operational backbone rather than being forced into generic software.

Conclusion

Expanding reach for agents and brokers isn’t simply a matter of growing headcount — it depends on whether the underlying technology can onboard new agents quickly, process policies efficiently at scale, and extend into segments like government insurance schemes without breaking down. Winsoft’s insurance distribution suite — SmartInsurance, AGENT, AGILE, and SmartPM Scheme — is built around exactly this need, giving distributors the operational foundation to grow their agent and broker network sustainably rather than simply making it bigger.
Categories
Blog

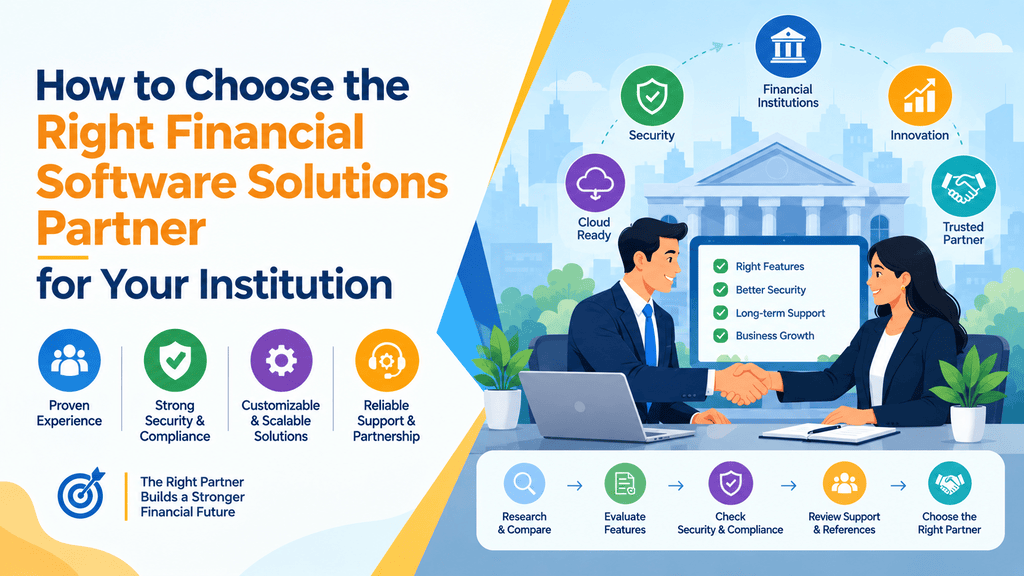
How to Choose the Right Financial Software Solutions Partner for Your Institution

Every bank, insurer, pension distributor, and wealth management firm eventually reaches the same decision point: build technology in-house, patch together multiple vendors, or partner with a single technology provider who understands the full BFSI landscape. Get this decision wrong, and institutions end up with fragmented systems that don’t talk to each other, vendors who understand software but not banking, or partners who can build a product but can’t support it for the next decade. Choosing the right Financial Software Solutions partner is one of the most consequential technology decisions a financial institution makes — and it’s worth being deliberate about what to actually evaluate.

Start With Domain Depth, Not Just Technical Capability

A common mistake institutions make is evaluating technology partners purely on technical merit — cloud architecture, API design, UI polish — without weighing how deeply the partner actually understands banking and financial services as a domain. Winsoft positions itself as the driving force behind strategic innovation in the financial world, offering state-of-the-art banking and financial solutions designed to meet the unique needs of today and tomorrow. That distinction matters: financial software isn’t generic enterprise software with a banking skin on it — it needs to be built around the specific operational, regulatory, and compliance realities of BFSI from the ground up.

A partner worth choosing should be able to help institutions create a better ecosystem of products and services for customers, spanning secure and compliant ecosystems on one end and customer-centric interfaces on the other. Both matter equally — a system that’s secure but unusable fails customers, and a system that’s customer-friendly but non-compliant fails regulators.

Check Whether the Partner Covers Your Full Product Landscape

One of the clearest signs of a partner built for long-term institutional relationships, rather than one-off projects, is breadth across the actual product lines a financial institution runs. This is worth checking line by line:

Banking and Capital Markets — Does the partner offer tools that streamline all banking processes with mission-critical enterprise software? Winsoft’s banking suite includes DeMATrix (depository participant solutions), eFDR (fixed deposit collateral management), SmartASBA (IPO and primary market application processing), SmartLocker (bank locker management), SmartLogistics, SmartSell, and SmartTax — covering the operational backbone banks actually run on, not just a single flagship product.

Insurance — For institutions running or supporting insurance distribution, the partner should deliver flawless process flows for life and non-life insurance distribution and comprehensive agent onboarding. This includes tools like AGENT and AGILE for agent onboarding and policy enrollment, alongside SmartInsurance for core distribution and SmartPM Scheme for government insurance scheme processing.

Pension — Institutions distributing pension products need a one-stop solution for NPS and APY distribution, covering back-office processing, subscriber-facing workflows, and touch-point management. This is where products like SmartNPS and SmartAPY come in.

Wealth Management — For wealth and mutual fund distribution, look for an integrated wealth management system for end-to-end management of financial asset classes — covering everything from mutual fund distribution (SmartMutual) to reconciliation (SmartRecon), payout processing (SmartPayout), sovereign gold bonds (SmartSGB), and broader wealth platforms (SmartWealth).

If a potential partner only covers one or two of these areas, institutions may find themselves right back where they started — stitching together multiple vendors — just a few years down the line as their product lines expand.

Evaluate the Services Layer, Not Just the Products

Software products alone aren’t enough. The right partner should also offer the services layer that keeps those products running, evolving, and properly staffed:

  • Digital Transformation Services — the ability to create exceptional customer experiences using analytics, automation of software tools, and cloud, with the right mix of industry expertise. This matters because most institutions aren’t just buying a product; they’re modernizing how they operate, and that requires strategic, not just transactional, support.
  • Testing Services — ensuring robust and reliable software applications with top-quality engineering and holistic testing solutions. In BFSI, where software failures carry direct financial and regulatory consequences, this isn’t optional — it’s foundational.
  • IT Staff Augmentation — talented and technical resources that can fulfill short-term and long-term IT staffing needs. Implementation and scaling phases often require additional technical capacity that doesn’t make sense to hire permanently, and a partner who can flex resourcing accordingly adds real operational value.
  • Turn-Key Projects & Product Re-Engineering — backed by 25+ years of expertise in managing a customer’s application life-cycle. This signals a partner capable of taking ownership of a project end-to-end, rather than delivering a component and stepping away.

Institutions evaluating partners should ask directly: can this partner support us not just at go-live, but through the years of maintenance, staffing fluctuations, and re-engineering that inevitably follow?

Look at Track Record and Longevity

Technology in BFSI isn’t a short-term relationship — core systems often run for a decade or more, and switching partners mid-stream is expensive and risky. This makes a partner’s track record genuinely important to weigh. Winsoft was founded in 1993 and has earned a unique reputation for its solutions and delivery excellence serving all the top blue-chip organizations in the BFSI industry. Longevity in a space as regulation-heavy and technically demanding as financial services is itself a signal — a partner who has operated through multiple regulatory cycles, technology shifts, and market conditions has proven staying power that a newer vendor hasn’t yet had the chance to demonstrate.

It’s also worth looking at who else trusts the partner. A provider serving innovative and inspiring companies across the globe, with the privilege of a strong client base in banking and financial solutions, gives institutions a reasonable degree of confidence that the partner can operate at the scale and compliance level their own institution requires.

Practical Questions to Ask When Evaluating a Partner

Bringing this together into a practical checklist, institutions should be asking:

  1. Does the partner understand our specific product line — banking, insurance, pension, or wealth management — deeply, or are they generalists?
  2. Can they support us across multiple product areas as our institution grows, rather than requiring a new vendor for each new business line?
  3. Do they offer services beyond the software itself — digital transformation, testing, staff augmentation, re-engineering — that we’ll need over the system’s lifecycle?
  4. How long have they operated in BFSI specifically, and what does their client base look like?
  5. Can they balance compliance and security with genuinely usable, customer-centric interfaces, rather than sacrificing one for the other?

Why This Decision Extends Beyond a Single Product Purchase

Choosing a financial software solutions partner is rarely just about one product. Institutions that start with, say, a Banking Technology Solutions need often find themselves later expanding into wealth management, pension distribution, or insurance technology as their business grows. A partner capable of supporting that full journey — rather than one that only solves today’s immediate problem — saves institutions from repeating this entire evaluation process every few years.

Conclusion

The right financial software solutions partner isn’t necessarily the one with the flashiest product demo — it’s the one with genuine BFSI domain depth, coverage across the product lines an institution actually runs (banking, insurance, pension, and wealth management), a services layer that supports the full technology lifecycle, and a track record proven over years, not months. Institutions that evaluate partners against this fuller picture — rather than a single point solution — are far better positioned for a technology relationship that scales with them, instead of becoming another system they’ll need to replace in a few years.

Categories
Blog

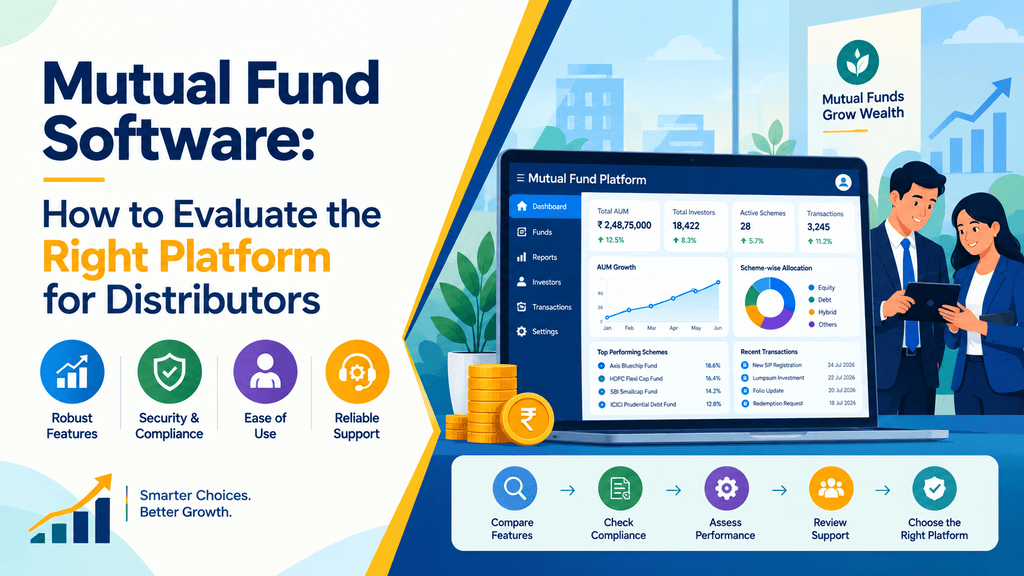
Mutual Fund Software: How to Evaluate the Right Platform for Distributors

Mutual fund distribution has changed dramatically over the past decade. What used to run on paper application forms, manual reconciliation, and disconnected spreadsheets is now expected to run as a fully digital, multi-channel business — one where customers onboard themselves online, RMs manage portfolios from a dashboard, and revenue reconciliation happens automatically instead of at month-end panic. For banks and financial institutions looking to scale their mutual fund distribution business, choosing the right Mutual Fund Software isn’t a minor IT decision — it directly determines how efficiently the business runs and how much revenue leakage gets caught before it becomes a problem. Here’s what actually matters when evaluating a platform, based on what a comprehensive solution needs to deliver.

Start With the Core Business Problem It Solves

Before comparing feature lists, it’s worth being clear about what mutual fund software is actually meant to fix. Banks and financial institutions are automating their mutual fund distribution to scale the business with ease, accuracy, and reduced total cost of ownership (TCO). The shift is from costly paper trails to digitized customer onboarding — meaning the platform you choose should fundamentally change how customers get onboarded, not just digitize the same manual process. If a platform still requires physical forms, manual verification, or offline risk profiling, it isn’t solving the core problem distributors actually have.

Evaluate Whether It Covers the Full Business, Not Just One Function

A common mistake distributors make is evaluating mutual fund software purely on its customer-facing features. But a platform built for serious scale — the kind used by leading mutual fund distributors in India — needs to function across the entire business, not just the sales end. This means looking for a platform that offers:

  • A Back Office for managing operations at the central office level
  • A Sales/RM interface to facilitate branch-level operations
  • A Customer interface for direct client interaction

When these three layers are properly integrated — rather than bolted together as separate systems — data flows consistently between them, which is what actually reduces operational overhead rather than just shifting the paperwork problem from physical to digital.

Check the Customer Portal Against Real Digital Expectations

The customer-facing layer is where most distributors focus first, and rightly so — it’s what determines whether customers actually adopt the digital channel instead of falling back on RM-assisted paper processes. A strong customer portal should offer:

  • Instant digital onboarding with eKYC and risk profiling — not a multi-day manual verification process
  • A comprehensive portfolio dashboard, giving customers real visibility into their holdings
  • Instant digital goal planning and tracking, so customers can map investments to actual financial objectives
  • Digital transaction execution for both lumpsum and systematic investments, since most mutual fund business runs on a mix of one-time and recurring transactions
  • Performance analytics and alerts, keeping customers informed without requiring them to log in constantly
  • Digital non-financial transaction execution, covering the administrative changes customers need to make outside of buying and selling
  • Support for handheld devices and responsive design, since a growing share of investment activity happens on mobile
  • Call center-assisted transaction execution, for customers who still prefer human assistance
  • A cart facility, allowing customers to build and execute multi-scheme transactions in one flow

If a platform is missing several of these, it’s likely to push more transaction volume back onto RMs manually — defeating the purpose of digitization in the first place.

Assess the Advisor/RM Portal Just as Carefully

Distributors sometimes underweight the RM-facing side of the platform, but this is where day-to-day business actually gets managed at scale. A platform worth evaluating seriously should give RMs:

  • A comprehensive RM/advisor dashboard
  • Full customer portfolio visibility with analytics, not just raw transaction data
  • Comprehensive RM/advisor reports, supporting performance tracking and client reviews
  • RM-assisted customer onboarding and re-risk profiling, for the customers who still need human guidance
  • RM-assisted transaction execution
  • RM-assisted scheduling of reports and alerts
  • Prospect and campaign management, supporting business development, not just servicing
  • RM targets and incentive management, tying the platform directly into how the distribution business actually motivates its sales force

This is a meaningful differentiator: platforms that treat RMs as an afterthought tend to force advisors into workarounds, which erodes both productivity and data accuracy over time.

Look Closely at the Operations Layer — This Is Where Revenue Leakage Happens

If there’s one area that separates genuinely enterprise-grade mutual fund software from a basic digital front end, it’s the operations layer. This is where revenue accuracy, reconciliation, and system integration actually get handled, and it should include:

  • Integration with various data service providers
  • Integration with existing core systems, so the mutual fund platform doesn’t operate as an isolated silo
  • Rule-based revenue calculation covering upfront, annualized, trail, incentive, and claw-back structures — mutual fund revenue models are genuinely complex, and a platform that can’t handle all of these accurately will produce revenue disputes
  • Automated revenue reconciliation, which is critical: accurate, software-driven reconciliation of income calculation with RTA data means distributors can plug revenue leakage that would otherwise go unnoticed in manual processes
  • Seamless order processing via interfacing with RTA and BSE Star
  • Customer portfolio returns calculation
  • RTA interface for reverse feeds covering transactions, NAV, and income data
  • A comprehensive, customizable reporting module
  • Integration with a Document Management System

When evaluating platforms, this is the layer worth stress-testing the hardest — because errors here directly translate to lost revenue, not just operational inconvenience.

Don’t Overlook Business MIS Reporting

Beyond day-to-day operations, distributors need visibility into how the business is actually performing. The right platform should provide Business MIS covering:

  • Assets Under Management (AUM) reports
  • Mobilization reports
  • Income reports
  • Active systematic (SIP) reports
  • YTD and MTD business reports
  • Zone-wise business reports

Without this level of reporting, distributors are left making business decisions on incomplete data — which becomes a bigger problem as the distribution business scales across more branches, zones, or advisor teams.

Practical Evaluation Criteria to Apply

Pulling this together, here’s what to actually check when comparing mutual fund software options:

  1. Does it eliminate paper-based onboarding entirely, or just digitize part of the process?
  2. Does it support multiple digital channels — customer portal, handheld devices, call center, and RM-assisted — so customers can transact however they prefer?
  3. Does the operations layer handle rule-based revenue calculation across all common structures (upfront, trail, incentive, claw-back)?
  4. Is revenue reconciliation automated against RTA data, or does it still require manual matching?
  5. Does it integrate with your existing core systems, or would it operate as a disconnected add-on?
  6. Is it proven at scale — used by leading distributors, and implemented across global banks and financial institutions?
  7. Is it built to extend, with scalable, extensible functionality as the business grows, rather than requiring a platform switch later?

Why This Matters Beyond Mutual Fund Distribution

A platform like SmartMutual is one part of a broader wealth management ecosystem, and it’s worth evaluating mutual fund software with that bigger picture in mind. The same platform philosophy — integrated back office, advisor tools, and automated reconciliation — extends across Winsoft’s Wealth Management Platform, which supports end-to-end management of financial asset classes beyond just mutual funds. For distributors managing multiple product lines, evaluating how well a mutual fund platform fits into (or connects with) this wider ecosystem is just as important as evaluating its standalone features.

Implementing a platform of this depth — with integrations spanning core banking systems, RTAs, exchanges, and data service providers — also typically requires dedicated technical capacity during rollout. Many distributors turn to IT Staff Augmentation to support implementation and integration phases without committing to long-term hires solely for a rollout period. And because a platform this central to the business often anchors a wider modernization effort, mutual fund software evaluations frequently happen alongside broader Digital Transformation Services initiatives, rather than as an isolated technology purchase.

Conclusion

Evaluating mutual fund software properly means looking well beyond the customer-facing app. The right platform for distributors needs to work across four layers — customer portal, advisor/RM portal, operations, and business MIS — with genuine integration between them, accurate rule-based revenue calculation, and automated reconciliation that catches revenue leakage before it becomes a recurring loss. Distributors who evaluate platforms against this full picture, rather than just the sales-facing interface, are far more likely to choose a system that scales with the business instead of becoming another operational bottleneck.

Categories
Blog

Government Insurance Scheme Software: Digitizing Social Security Delivery in India

Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) and Pradhan Mantri Suraksha Bima Yojana (PMSBY) are two of India’s largest social security insurance schemes, designed to bring life and accident insurance coverage to millions of citizens who might otherwise remain uninsured. Banks and financial distributors are the primary channel through which these government schemes reach the public — which means the onboarding, renewal, and premium management for these schemes runs directly through bank branches and digital banking channels. Managing this at national scale, across recurring annual renewal cycles, is not something that works well with manual processes. This is exactly the gap that purpose-built Government Insurance Scheme Software is designed to close.

Why PMJJBY and PMSBY Need Dedicated Technology

PMJJBY is a government-backed life insurance scheme, while PMSBY is a government-backed accident insurance scheme — both offered to Indian citizens through participating banks. Winsoft’s SmartPM Scheme was built specifically to digitize this process. Notably, Winsoft’s Jan Suraksha Portal APIs are now live and available, reflecting direct integration with the government infrastructure these schemes run on.

The core purpose of the platform is straightforward: digitization of government-based insurance schemes to enable financial distributors to serve their clients efficiently, at the volume these national schemes demand. For a bank, this isn’t a one-time onboarding exercise — PMJJBY and PMSBY both require annual renewal, meaning the operational workload repeats every year for every enrolled customer, across potentially millions of policyholders nationally.

Understanding the PMJJBY Module

The PMJJBY module allows customers to onboard and auto-renew for the scheme, which — as a government-backed life insurance product — needs to work reliably at scale. Importantly, the system is flexible to integrate with any life insurance provider, meaning banks aren’t locked into a single insurer’s technical infrastructure to offer this scheme to their customers. This flexibility matters because different banks partner with different insurers for PMJJBY coverage, and a rigid, single-insurer system would limit which banks could realistically deploy the platform.

Understanding the PMSBY Module

Similarly, the PMSBY module allows customers to onboard and auto-renew the premium for the accident insurance scheme. Like its PMJJBY counterpart, this module is flexible to support any general insurance provider, giving banks the same freedom to work with their chosen insurance partner rather than being constrained by the software itself.

Together, these two modules mean a bank can offer both of India’s flagship social security insurance schemes through a single unified platform, rather than managing separate systems or manual processes for each.

How SmartPM Scheme Handles the Full Process

SmartPM Scheme is a comprehensive, browser-based and mobile-responsive solution offering Back Office, Front Office, and online APIs for processing the onboarding and renewal of customers under both PMJJBY and PMSBY. This three-part structure means the platform isn’t just a data-entry tool — it covers the complete operational chain from a customer walking into a branch (or applying digitally) to the scheme being processed on the back end and renewed automatically each year.

Core Processing Capabilities

At the heart of the platform, PMJJBY and PMSBY processing covers:

  • Onboarding — enrolling new customers into the scheme
  • Recurring premium — handling the annual premium cycle that both schemes require
  • Account closure — managing exits from the scheme when needed

This covers the entire customer lifecycle within the scheme, not just the initial sign-up, which is critical given how much of the operational burden in government scheme distribution comes from ongoing renewal management rather than first-time enrollment.

Dashboard Visibility

A dashboard gives banks and distributors visibility into scheme performance and processing status — important when managing enrollment and renewal activity across potentially thousands of branches simultaneously.

Integration With Insurance Companies

The platform supports both file-based and API-based integration with insurance companies, giving banks flexibility depending on how their insurance partners are set up technically. This dual-integration approach means the platform can work with insurers who have modern API infrastructure as well as those still relying on file-based data exchange.

Premium Collection and Reversal

Initial premium collection is built into the platform, along with a reversal of premium amount in case of rejected requests — an important operational safeguard, since not every enrollment request will be successfully processed by the insurer, and customers need their premium refunded promptly when that happens.

Compliance and Control

Maker and Checker functionality, configurable as per each bank’s requirement, ensures the platform meets internal audit and control standards that banks operate under — a non-negotiable requirement for any system handling customer financial data and government scheme enrollment at scale.

Reporting

MIS reports provide the visibility banks and regulators need into scheme performance, enrollment numbers, and renewal rates — data that’s essential given the public accountability attached to government-backed insurance schemes.

API-First, Digitally Native Architecture

The platform offers consumable APIs for digital journeys and integrates with Core Banking systems via APIs, meaning PMJJBY and PMSBY enrollment can be embedded directly into a bank’s existing digital banking channels rather than existing as a separate, disconnected system. Winsoft describes the platform as easy and simple to use, yet flexible to integrate — a combination that matters given how varied core banking environments are across different banks.

Key Benefits for Banks and Distributors

Pulling these capabilities together, SmartPM Scheme delivers a set of practical benefits for banks managing government insurance scheme distribution:

  • Mobile-responsive application, supporting access across devices
  • Simplified onboarding journey, reducing friction for both customers and branch staff
  • Automated renewal process, addressing the single biggest recurring operational burden in scheme management
  • SMS and email alerts, keeping customers informed about enrollment status and renewal dates
  • Attractive dashboard, giving stakeholders clear visibility into scheme performance
  • Flexibility for customization, allowing the platform to adapt to a bank’s specific operational and insurer-partnership needs

Fitting Government Scheme Distribution Into a Bank’s Broader Strategy

Government insurance scheme distribution doesn’t operate as an isolated function — it’s typically one part of a bank’s broader financial inclusion and digital strategy. Banks investing in platforms like SmartPM Scheme are often doing so as part of wider Digital Transformation Services initiatives, modernizing customer onboarding, digital channels, and back-office operations across multiple product lines simultaneously — not just for PMJJBY and PMSBY, but as part of a connected digital banking ecosystem.

Because SmartPM Scheme integrates deeply with core banking systems and insurance company APIs, implementation and rollout often require additional technical capacity, particularly during integration and testing phases. This is where banks frequently rely on IT Staff Augmentation to bring in the technical resources needed without committing to long-term hires purely for a rollout period.

It’s also worth noting that government scheme distribution sits alongside Winsoft’s broader insurance distribution capabilities. Just as SmartPM Scheme handles PMJJBY and PMSBY specifically, Winsoft’s Insurance Distribution Software (SmartInsurance) handles the broader life and non-life insurance distribution a bank might offer alongside government schemes — meaning a bank’s insurance distribution technology strategy can cover both private and government-backed products through a connected suite rather than fragmented, standalone systems.

Conclusion

PMJJBY and PMSBY are national-scale social security schemes that depend on banks to reach citizens effectively — and that only works if the underlying technology can handle high-volume onboarding, automated annual renewals, and insurer integration without breaking down. SmartPM Scheme’s Back Office, Front Office, and API-driven architecture give banks a single, purpose-built platform to manage the complete lifecycle of both schemes — from first enrollment to automated renewal, premium reversal, and compliance reporting — turning what could be an overwhelming manual burden into a streamlined, auditable digital process.

Categories
Blog

IPO Processing Software: Streamlining Primary Market Operations for Banks

Every time a company launches an IPO, FPO, NCD, NFO, or Rights Issue in India, banks sit at the center of the action — collecting applications, blocking funds through ASBA, coordinating with exchanges, and reconciling thousands (sometimes lakhs) of applications within tight regulatory timelines. For a bank, this isn’t a once-a-year event; with India’s active primary market, it’s a recurring operational cycle that demands accuracy, speed, and audit-readiness every single time. Managing this manually, or with fragmented tools, is where banks run into bottlenecks, reconciliation errors, and compliance risk. This is exactly the problem purpose-built IPO Processing Software is designed to solve.

Why Primary Market Processing Needs Dedicated Technology

Primary market applications aren’t a simple, single-step transaction. An IPO or NCD application moves through registration, verification, fund blocking, allotment, and reconciliation — often across multiple channels and involving coordination between the bank’s core systems, the exchanges (NSE and BSE), and depositories. Winsoft’s SmartASBA was built specifically around this reality: a comprehensive digital platform for IPO, NFO, Debt/NCD, and Rights Issue products that digitizes primary market application processing so financial distributors can handle, support, and service their clients without the operational chaos that comes with manual processing.

The platform’s core purpose is straightforward but critical: automated processing of bulk Primary Market applications, supporting hassle-free investments through ASBA, Syndicate ASBA, and Physical/Non-ASBA applications — covering the full range of ways investors actually apply for primary market products in India today.

Back Office: The Operational Backbone

The Back Office module is where the heavy lifting of IPO processing happens. It manages the primary market schemes themselves — IPO, FPO, DEBT/NCD, NFO, and Rights Issue — from a single administrative layer. What makes this particularly useful for banks is the depth of integration built into it:

  • Integration with Core Banking Systems like Finacle and FlexCube, handling lien marking, lien removal, and fund transfer automatically — eliminating the manual coordination that typically happens between a bank’s IPO team and its core banking operations team.
  • Integration with SMS/Email gateways and online PAN verification via NSDL, along with an application registration API for third-party brokers, so applications coming through broker channels don’t require separate manual entry.
  • Bulk upload support for application forms, which matters enormously during high-volume issues where thousands of applications need to be processed within a narrow window.
  • API and file-based interfaces with NSE and BSE for application processing, keeping the bank’s system in sync with exchange requirements without manual file handling.
  • Maker/Checker controls across all masters and transactions, satisfying the audit and security requirements that any bank handling investor funds must meet.
  • Dispatch management covering registration, verification, and acceptance stages, so the status of every application is tracked and auditable.
  • Cut-off time management for HNI and retail categories, applied consistently across branches and the central office — critical because primary market issues have strict regulatory cut-off windows that differ by investor category.
  • The ability to handle modifications in application data post issue closure, and comprehensive reconciliation for both applications and funds processed — arguably the single most important capability for a bank, since reconciliation errors in primary market processing carry direct financial and regulatory consequences.

Branch Office: Where Applications Actually Get Processed

While the Back Office handles scheme-level administration, the Branch Office module is where day-to-day application handling happens. It supports both bidding and fixed-price issues, covering the two primary structures IPOs and other primary market products can take. Branch staff get:

  • Application entry, modification, verification, and cancellation capabilities directly at the branch level
  • A dashboard for monitoring the application registration-to-allotment process, giving branch and central teams real-time visibility into where every application stands
  • An application form printing module, supporting the physical/non-ASBA application channel alongside digital ones

This combination means a bank’s branch network can process primary market applications consistently, whether the investor applies digitally or in person.

ASBA On-Net: Extending Access Through Digital Channels

Beyond the branch counter, ASBA On-Net extends primary market access through digital channels — which is increasingly where investor demand sits. This module includes:

  • A scheme and application dashboard for digital visibility
  • Beneficiary registration and modification capabilities
  • Application bid, rebid, and withdrawal functionality — important because investors frequently need to revise their bids before an issue closes
  • API-based interfaces for mobile, enabling investment through handheld devices
  • Seamless integration with the retail banking portal, so investors can apply for IPOs and other primary market products through the same digital banking experience they already use

Together with the Back Office and Branch Office, this gives banks multiple digital application channels — investors can invest through internet banking, handheld devices, or channel partners, all feeding into the same processing backbone.

Business Reports: Built for Regulatory Scrutiny

Primary market processing is one of the most heavily scrutinized areas of capital market operations, and the Business Reports module reflects that. It includes MIS reports, audit reports, posting reports, SEBI reports, product-wise reports, and compliance reports as per the requirements of SEBI, NSE, and BSE. For a bank’s compliance and audit teams, having these reports generated directly from the processing platform — rather than assembled manually after the fact — significantly reduces both the effort and the risk involved in regulatory reporting.

Key Benefits for Banks and Financial Distributors

Pulling these modules together, SmartASBA delivers a set of practical operational benefits:

  • Support for bulk imports of application requests, essential during high-subscription IPOs
  • Fully automated, web-based, open-source architecture, reducing dependency on legacy infrastructure
  • API-based architecture that integrates with brokers and securities channels for application processing through the back office
  • Granular-level user access control, supporting internal security requirements
  • Web-responsive user interface, usable across devices
  • SMS and email alert support, keeping both staff and investors informed throughout the application lifecycle
  • Automated income and commission calculation, which simplifies billing and invoice generation — a process that’s traditionally manual and error-prone when done issue-by-issue
  • Accurate, comprehensive reconciliation, ensuring the application-to-fund workflow closes cleanly every time

Fitting IPO Processing Into a Bank’s Broader Technology Strategy

Primary market processing rarely sits in isolation from a bank’s wider technology roadmap. Banks that invest in dedicated IPO processing infrastructure are often doing so as part of a broader Digital Transformation Services initiative — modernizing capital market operations alongside core banking, retail digital channels, and other business lines simultaneously, rather than treating IPO processing as a standalone upgrade.

Given how integration-heavy a platform like SmartASBA is — connecting to core banking systems, exchanges, depositories, and broker networks — implementation often requires additional technical bandwidth during rollout. This is where banks frequently rely on IT Staff Augmentation to bring in the technical resources needed for integration and testing phases, without committing to long-term hiring cycles.

It’s also worth noting that this same integration-first approach extends across Winsoft’s capital market suite. Just as SmartASBA connects primary market processing directly into a bank’s core systems, Winsoft’s broader Banking Technology Solutions suite is built around the same principle — giving banks purpose-built, deeply integrated platforms for each capital market function rather than forcing generic software to handle specialized, high-volume, regulation-heavy processes.

Conclusion

IPO and primary market processing is high-stakes, high-volume, and tightly regulated — which makes it a poor fit for manual processes or generic financial software. SmartASBA’s Back Office, Branch Office, ASBA On-Net, and Business Reports modules together give banks and financial distributors a single, integrated platform to manage the entire application lifecycle — from bulk registration and core banking integration to SEBI-compliant reporting and accurate reconciliation — turning what used to be a high-risk manual process into a streamlined, auditable digital workflow.

Categories
Blog

Bancassurance Software: Bridging Banking and Insurance Distribution

Bancassurance — the practice of banks distributing insurance products alongside their core banking services — has become one of the fastest-growing insurance distribution channels in India. For a bank, this isn’t a small side project. It means taking on an entirely new layer of operations on top of everyday banking: policy onboarding, renewals, relationship manager (RM) training, premium collection, and compliance reporting. Without the right technology backbone, this quickly turns into a manual, fragmented, and error-prone process — one that can end up costing more than it earns. This is exactly where dedicated Bancassurance Software makes the difference between a bancassurance channel that scales smoothly and one that becomes an operational headache.

Why Bancassurance Needs Purpose-Built Technology, Not Generic Tools

When a bank decides to distribute insurance, it is effectively running two businesses through one channel — banking and insurance — often with the same branch staff handling both. Many banks initially try to manage this with spreadsheets, manual registers, or insurance-company-provided tools that weren’t designed with a bank’s scale or workflow in mind. The result is usually duplicate data entry, delayed renewals, inconsistent reporting, and RMs who are undertrained on the insurance side of their job.

Winsoft’s insurance solutions are built specifically for the insurance distribution industry, using technology designed to automate the business processes of insurance distribution. That distinction matters: this isn’t insurance software repurposed for banks — it’s built around the reality that insurance distribution, at scale, needs its own dedicated back office, front office, and reporting layer, separate from (but connected to) a bank’s core banking systems.

Smart Insurance: The Operational Core of Bancassurance

At the center of a bank’s bancassurance operations sits SmartInsurance, a comprehensive solution for life and non-life insurance distribution. For a bank running high policy volumes across hundreds of branches, this translates into three practical capabilities:

  • A seamless Back Office that manages the processing workload insurance distribution generates — policy issuance, renewals, endorsements, and the administrative volume that comes with selling insurance at branch scale.
  • A user-friendly Front Office, which matters because the people actually selling these policies are bank staff, not insurance specialists. A system that’s intuitive enough for branch employees to use without extensive retraining is what keeps adoption high and errors low.
  • An exhaustive reporting feature, because bancassurance brings its own compliance and audit requirements that sit alongside — but are distinct from — a bank’s existing regulatory reporting. Insurance regulators, product partners, and internal audit teams all need visibility into how policies are being sold and serviced, and manual reporting simply doesn’t hold up at scale.

Together, these three pieces mean a bank isn’t just “adding insurance products” to its counter — it’s running a properly managed second business line with the operational rigor that requires.

Solving the RM Training Bottleneck

One of the most underestimated challenges in bancassurance is people, not technology. Bank RMs are trained bankers — they aren’t insurance professionals by default, and turning them into competent insurance distributors takes structured onboarding and ongoing training. Do this manually, through classroom sessions and paper certification records, and it becomes one of the biggest bottlenecks to scaling a bancassurance channel across a large branch network.

Winsoft addresses this directly with AGENT, an Automated General & Life Insurance Training Tracker System built specifically for the insurance distribution industry. It empowers insurance distributors to onboard their RMs digitally — which means a bank can bring hundreds of RMs across multiple branches up to speed on insurance products and compliance requirements without building a manual training program from the ground up. For a bank with an expanding branch network, this digital onboarding capability is often what separates a bancassurance rollout that scales in months from one that takes years.

Managing the Full Policy Lifecycle, Not Just the Sale

Selling a policy is only the beginning. What happens after — renewals, premium collection, endorsements — is where most bancassurance operations lose efficiency if there’s no automation in place. This is where AGILE, Winsoft’s Automated General Insurance & Life Insurance Enrolment System, comes in. It covers the policy lifecycle from entering a new policy of the insured person to automating the yearly premium payment.

For a bank managing thousands of policies sold through its branches, this lifecycle automation is what keeps the bancassurance business profitable rather than becoming an administrative drain. Manual premium follow-ups and renewal tracking don’t scale — automated systems do, and they also reduce the compliance risk that comes with missed renewals or premium lapses.

Supporting Government Insurance Schemes Through Bank Branches

In India specifically, banks aren’t just distributing private insurance products — they’re often the primary channel through which government insurance schemes reach citizens, particularly in semi-urban and rural areas. Winsoft’s SmartPM Scheme is built for exactly this role. It’s a browser-based and mobile-responsive solution that offers Back Office, Front Office, and online APIs for processing the onboarding and renewal of customers under Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY) and Pradhan Mantri Suraksha Bima Yojana (PMSBY).

This matters because government scheme distribution comes with its own operational patterns — high enrollment volumes, seasonal renewal cycles, and reporting requirements tied to government mandates — that differ from how a bank might sell a private life insurance policy. Having a system built specifically to handle PMJJBY and PMSBY onboarding through APIs means banks can plug this into their existing digital channels rather than running it as a separate manual process.

Bancassurance as Part of a Bigger Digital Banking Strategy

Bancassurance rarely happens in isolation. For most banks, introducing or scaling a bancassurance channel is one part of a much broader push toward operational modernization. Many banks that invest in bancassurance technology are doing so alongside wider Digital Transformation Services initiatives — modernizing multiple business lines, including insurance distribution, banking operations, and customer-facing digital channels, at the same time.

Scaling a new distribution channel like bancassurance also puts pressure on technical teams, particularly during implementation and integration phases. This is where banks often turn to IT Staff Augmentation — bringing in additional technical resources for the duration of a rollout without committing to long-term hiring, so the bancassurance implementation doesn’t stall waiting for internal bandwidth.

It’s also worth noting that this same underlying philosophy — giving a bank a dedicated, purpose-built platform for a secondary distribution business — applies beyond insurance. Winsoft’s Pension Distribution Solution follows the same principle for banks distributing National Pension System products, reinforcing a broader pattern: as banks take on more third-party financial products, each distribution line benefits from its own dedicated operational backbone rather than being forced into generic, one-size-fits-all systems.

Why This Matters for Banks Right Now

As competition among banks intensifies and interest income margins come under pressure, fee-based income from bancassurance has become an increasingly important revenue stream. But that revenue only materializes if the operational side — onboarding, training, policy servicing, renewals, and compliance reporting — can actually keep pace with sales ambitions. A bank that sells aggressively but services poorly ends up with high lapse rates, frustrated customers, and regulatory scrutiny, all of which erode the very revenue bancassurance was meant to generate.

Conclusion

Bancassurance offers banks a genuine, scalable growth opportunity — but only when the technology behind it can support the full lifecycle, from RM training to policy servicing to government scheme processing. Winsoft’s insurance distribution suite — SmartInsurance, AGENT, AGILE, and SmartPM Scheme — is built to handle exactly this, giving banks a single, automated foundation to run insurance distribution alongside their core banking business, without it becoming an operational burden.

Categories
Blog

Retirement Management Software: Helping Institutions Manage Pension Portfolios

Retirement planning in India spans a genuinely wide range of subscribers, government employees, private sector professionals, and workers in the unorganised sector alike, each engaging with different pension products under different rules. For the banks and financial institutions serving these subscribers, managing this range of pension offerings through disconnected, manual processes becomes increasingly difficult as subscriber volumes grow.

Retirement Management Software exists to bring structure to this responsibility, giving institutions a way to manage pension portfolios across products, from registration through to ongoing servicing, within a connected system.

Why Institutions Need a Broader Approach to Pension Administration

Financial institutions rarely serve subscribers under just one pension scheme. Many manage a portfolio of retirement products simultaneously, each with its own registration process, contribution rules, and reporting requirements. Handling this range manually, through separate spreadsheets or disconnected systems for each product, creates unnecessary complexity and increases the risk of errors as subscriber numbers scale.

A more structured approach typically supports:

  • Subscriber registration and onboarding across multiple pension products.
  • Bulk instruction processing for contributions and account updates.
  • Business MIS reporting to track subscriber activity and portfolio health.
  • Both Back Office processing and Front Office sales capability within one system.

Supporting Different Pension Products Under One Structure

Institutions serving retirement-focused subscribers often need to manage more than one government-backed scheme at once. For subscribers investing through the National Pension System, institutions typically rely on National Pension Scheme Software to handle automated subscription and processing of investments, supported by seamless Back Office processing alongside Front Office sales capability.

For institutions also serving subscribers under the unorganised sector’s pension scheme, a separate but complementary system, commonly referred to as Atal Pension Yojana Software, handles the specific registration, contribution, and reporting requirements unique to that scheme. Because eligibility rules, contribution structures, and reporting requirements differ meaningfully between these schemes, institutions benefit from software that respects these differences rather than forcing every pension product through an identical, one-size-fits-all workflow.

How This Helps Institutions Manage Pension Portfolios More Effectively

Bringing multiple pension products under a coordinated technology structure changes how institutions actually operate day to day. Subscriber registrations move through digital workflows rather than manual paperwork. Bulk instructions, whether contribution processing or account updates, can be handled at scale rather than one record at a time. And business MIS reporting gives institutions a current view of subscriber activity and portfolio performance across products, rather than requiring separate reports pieced together manually for each scheme.

This matters particularly for institutions serving senior citizens and long-term subscribers, where accuracy and consistency directly affect the retirement outcomes these subscribers are relying on.

Why Online Subscriber Services Matter

Beyond back-office processing, subscribers themselves benefit from being able to manage their registrations and subscriptions online rather than depending entirely on branch visits. Institutions offering this kind of self-service access, alongside traditional branch support, tend to serve a broader range of subscriber preferences, from those comfortable managing accounts digitally to those who still prefer in-person assistance.

Conclusion

Managing pension portfolios across different retirement products requires more than a single, generic system, it requires software that respects the distinct rules of each scheme while still giving institutions a unified way to manage registrations, contributions, and reporting. Retirement Management Software built around this structure helps institutions serve senior citizens and long-term subscribers with greater accuracy and consistency, regardless of how many pension products they administer. For institutions managing this responsibility at scale, this kind of coordinated approach isn’t just operationally convenient, it directly supports the reliability subscribers depend on for their long-term retirement security.

FAQs

1. What does retirement management software actually help institutions do?

It helps institutions manage pension portfolios across multiple products, covering subscriber registration, bulk instruction processing, Back Office and Front Office operations, and Business MIS reporting.

2. Can one platform handle different pension schemes with different rules?

Yes, institutions typically use scheme-specific software, such as tools built around the National Pension System or Atal Pension Yojana, within a broader retirement management structure that respects each scheme’s distinct requirements.

3. Why is bulk instruction processing important for pension administration?

As subscriber numbers grow, processing contributions and account updates one at a time becomes unmanageable. Bulk processing allows institutions to handle these updates efficiently at scale.

4. Do subscribers need to visit a branch to manage their pension accounts?

No, institutions offering online subscriber services allow registrations and subscriptions to be managed digitally, alongside traditional branch-assisted support for those who prefer it.

5. What role does Business MIS reporting play in pension portfolio management?

It gives institutions a current, consolidated view of subscriber activity and portfolio performance across different pension products, rather than relying on separate manual reports for each scheme.

Categories
Blog

A Digital Transformation Story in Banking Operations

There is a particular kind of inefficiency that only shows up once you watch a process in person. Not in a systems diagram, not in a workflow chart — but in the everyday reality of someone physically carrying a sealed envelope from a bank branch to a clearing house, because that is how it has always been done.

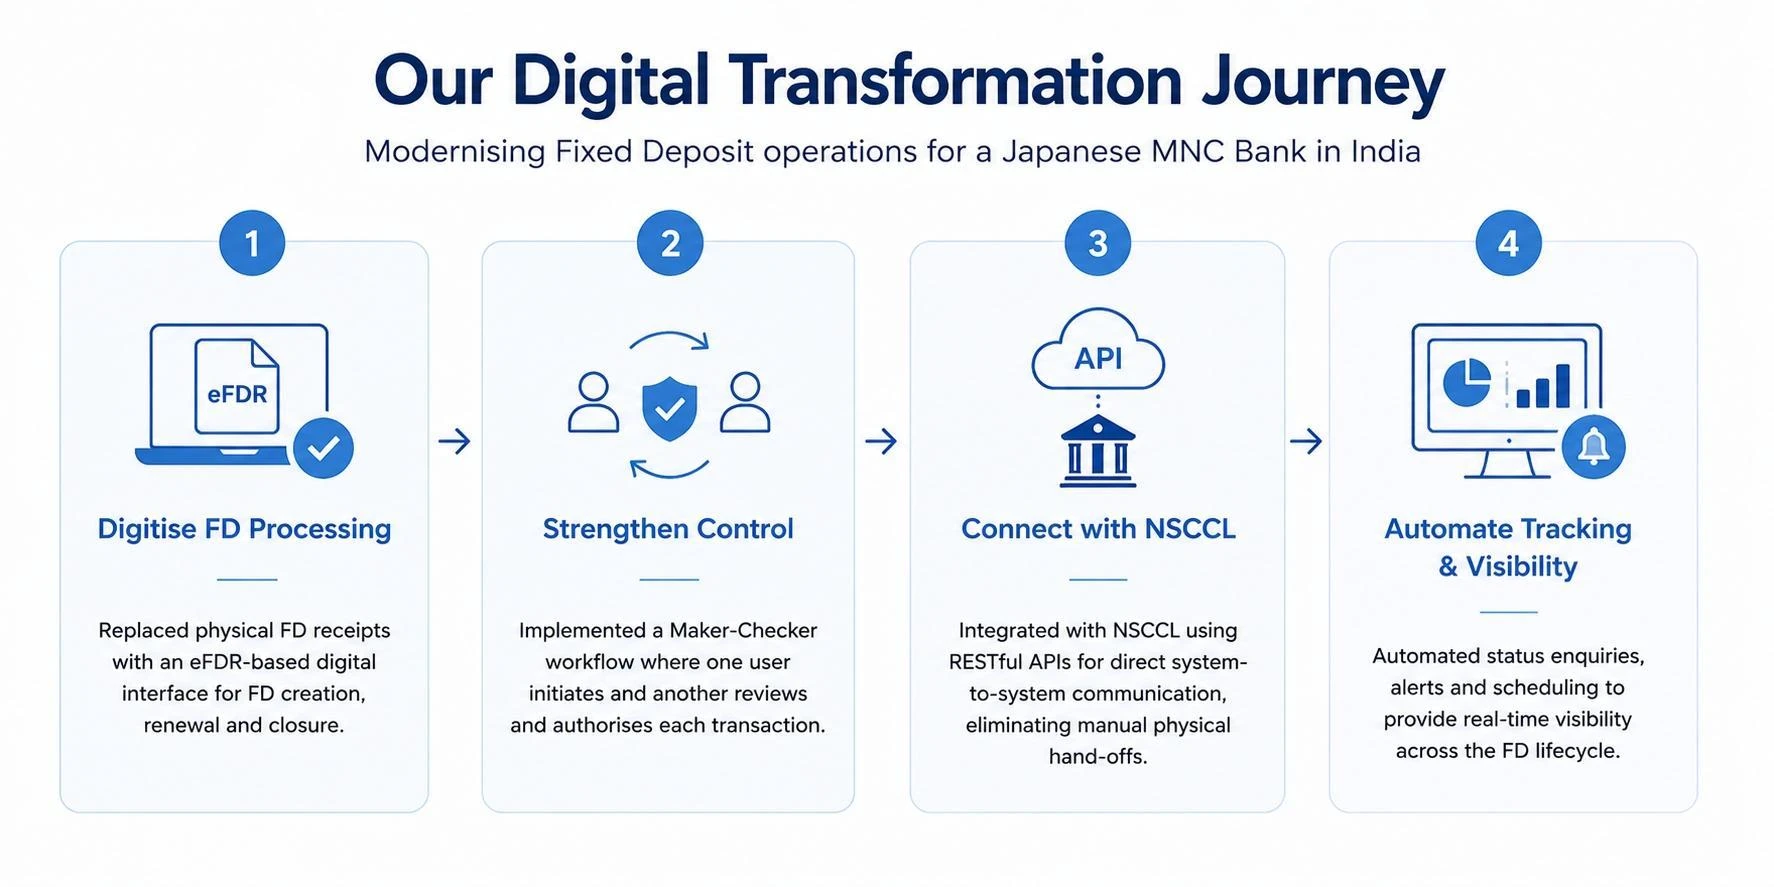
For one Japanese MNC bank operating in India, that process was Fixed Deposits for collateral management of foreign institutions that invest in Indian markets. The task on paper looked narrow: modernise how Fixed Deposit receipts were created, renewed and closed. In practice, it became a case study in what digital transformation actually requires — not just replacing paper with a screen, but rebuilding the operating model around control, traceability and integration.

The Problem Behind the Problem

The bank’s existing process required staff to physically collect sealed FD receipts from branches and hand-deliver them to NSCCL, India’s clearing corporation, for every creation, renewal or closure. Each transaction depended on someone being in the right place, at the right time, with the right paperwork. It worked — but it was slow, resource-intensive, and offered almost no real-time visibility into where any given FD stood in its lifecycle.

This is a familiar shape of problem for banking operations teams anywhere. Wherever a transaction still depends on physical movement of a document between two institutions, three things tend to follow: it’s slow, it’s hard to audit in real time, and it quietly consumes far more operational headcount than anyone budgets for.

Reimagining the Workflow, Not Just Digitising the Document

The instinct in many transformation projects is to scan the paper and call it done. We took a different starting point: what would this process look like if it were designed digital-first, with the same governance rigour a bank’s compliance function would demand?

That meant redesigning the workflow around a few core principles:

Replace physical movement with structured digital data. An eFDR-based interface now handles FD creation, renewal and closure electronically, removing the courier step entirely.

Integrate directly with market infrastructure. Rather than digitising the paperwork and still routing it manually, the solution connects to NSCCL through RESTful APIs — so FD creation, renewal and release happen as system-to-system transactions, not human hand-offs.

Keep human judgement where it matters, and only there. A Maker-Checker workflow ensures one user initiates a transaction and a second reviews and authorises it before it goes anywhere near NSCCL. Rejections are logged with reasons, so nothing disappears into a black box.

Make status a fact, not a follow-up call. Automated status enquiries and background scheduling track FD release progress and trigger alerts to the operations team the moment something changes — no more chasing updates.

Secure access the way an enterprise IT function expects. Active Directory-based authentication with group-based role mapping means access to each function is governed centrally, not managed through informal permissions.

The Pattern Underneath the Product

Strip away the specifics of FD operations and NSCCL, and a repeatable transformation pattern emerges — one that applies to a wide range of paper-dependent banking processes, not just this one:

Paper & Physical Movement → Digital Data Capture → Maker-Checker Control → API Integration → Automated Status Tracking → Alerts & Reporting

This is the sequence that matters more than any single product name. It’s the difference between digitising a document and re-engineering an operating model.

Why This Matters Beyond One Bank

Operational reports, API status reporting, consolidated FD reporting and full transaction/user activity logs now give the bank’s teams a live view of the FD lifecycle — the kind of visibility that used to require manual reconciliation, and now exists as a by-product of how the system is built.

The underlying challenge — legacy, paper-intensive processes sitting inside otherwise modern banks — is not unique to one institution or one market. Many banking operations teams, including here in the UK, are managing some version of the same problem: a critical process that still depends on physical documents, manual sign-off chains, or systems that don’t talk to each other. The tools differ by geography and regulation, but the underlying transformation logic — capture digitally, control deliberately, integrate directly, track automatically — holds regardless of which market it’s applied in.

That’s the capability this project really demonstrates: not a single product, but an approach to taking operationally critical, paper-bound banking processes and rebuilding them as connected, auditable, integration-ready digital workflows — without losing the controls a bank is required to have in the first place.

Categories
Blog

IT Staff Augmentation: A Smart Service for Bridging BFSI Talent Gaps

A mid-sized bank rolling out a new digital lending platform. An asset management company upgrading its trading interface before a regulatory deadline. An insurer building out a servicing portal for a growing policy book. None of these projects can wait six months for a hiring process to run its course, yet each one needs people who already understand how BFSI systems actually work, not developers learning the sector from scratch.

IT Staff Augmentation exists precisely for this gap, giving BFSI companies a way to bring in skilled technical resources quickly, without the extended timeline that comes with building a permanent team from the ground up.

The Kind of Projects This Typically Supports

This isn’t a one-size-fits-all service applied to any technical need. It tends to show up specifically in projects tied to:

  • Short-term initiatives with a defined scope and a fixed deadline.
  • Specialised platform work, core banking applications, Digital Banking Solutions, trading systems, or servicing portals, where general developers would need significant ramp-up time.
  • Periods of fluctuating demand, such as regulatory reporting cycles or new product launches, that don’t justify permanent hires.
  • Strengthening an existing core team temporarily, without long-term headcount commitments.

Why Domain-Specific Resources Make a Measurable Difference

A company evaluating this service is really asking one practical question: will bringing in external resources actually save time, or just move the learning curve somewhere else?

The answer depends heavily on domain fit. Resources with prior, hands-on experience across banks, asset management companies, NBFCs, insurance companies, and broking firms bring working knowledge of large-sized databases, Microsoft technologies, and specific BFSI functions, life and general insurance, pension schemes, mutual funds, Investment Management Software, demat operations, analytics reporting, and broader financial management software solutions. That kind of familiarity means a resource can start contributing to a project within days, rather than spending the first few weeks simply understanding how the business operates.

This becomes especially clear in specialised, high-stakes environments. A developer with prior exposure to IPO Processing Software, for instance, already understands concepts like application volume spikes, fund blocking logic, and exchange-linked processing timelines, context that would otherwise take considerable time to build from zero on a live, time-sensitive project.

How Engagements Are Typically Structured

Most engagements run on a Time & Material contract model. Rather than fixing the entire scope of work upfront, teams work closely with the client to build a project plan delivered across smaller, more manageable timelines, giving both sides room to adjust as the work progresses.

Under this model, billing is tied to actual time spent on development, and the client retains a more active role in shaping direction compared to a fixed-price arrangement. This tends to suit BFSI projects particularly well, since requirements can shift, a compliance clarification changes a spec, or early testing reveals a new priority, without needing to renegotiate the entire engagement each time.

What This Approach Solves in Practical Terms

Stripped down to the essentials, this service tends to address a specific set of recurring business problems:

  • Slow recruitment cycles that don’t match how quickly BFSI projects need to move.
  • Higher development costs associated with hiring permanently for temporary or specialised work.
  • Legal and administrative overhead that comes with direct employment arrangements.
  • Geographical hiring limitations, when the right skillset isn’t available locally.
  • Rigid team structures that can’t easily expand or contract as project needs change.

Where the Value Shows Up Over Time

Companies that use this service well tend to treat it as a genuine extension of their internal team, not a separate, disconnected group working in isolation. Augmented resources typically integrate into existing workflows and reporting structures, contributing toward the same deadlines and standards as permanent staff.

Over time, this flexibility tends to compound. A company can expand its technical capacity quickly when a new initiative demands it, and just as easily scale back down once that specific need has passed, without carrying the cost of permanent headcount built around a temporary requirement.

Conclusion

BFSI companies rarely face a shortage of technical talent in the abstract, they face a shortage of the right talent, available on the timeline a project actually needs. IT Staff Augmentation closes that specific gap, giving institutions access to professionals who already understand the sector’s systems and compliance context, engaged through a model flexible enough to adapt as project requirements evolve. For companies facing deadlines that standard hiring simply can’t meet, this remains one of the more practical ways to keep specialised BFSI projects moving forward.

FAQs

1. What kinds of BFSI projects benefit most from IT staff augmentation?

Projects with defined scopes and tight deadlines, specialised platform work, and periods of fluctuating technical demand tend to benefit most, since permanent hiring often can’t match these timelines.

2. Why does domain-specific experience matter so much in BFSI staffing?

Resources with prior exposure to banking, insurance, or investment platforms can start contributing within days, since they don’t need to learn the sector’s operational context from scratch.

3. How is billing typically structured for these engagements?

Most engagements follow a Time & Material contract, where companies are billed for actual time spent on development, offering more flexibility than a fixed-price project.

4. Does augmented staff replace a company’s internal technology team?

No, augmented resources typically work as an extension of the existing team, integrating into current workflows rather than operating as a separate unit.

5. Can a company scale its augmented team down once a project ends?

Yes, one of the core advantages of this approach is the ability to scale up for a specific need and scale back down once that work is complete.

Categories
Blog

IT Staffing Solutions: How to Scale Your Tech Team Quickly

Technology projects rarely wait for a company’s hiring process to catch up. A new project gets approved, a deadline gets set, and suddenly a team needs specialised skills or simply more hands than it currently has. Traditional hiring, sourcing, interviewing, negotiating, onboarding, can take months, a timeline that often doesn’t match how quickly business needs actually move.

This is where IT Staffing Solutions offer a practical alternative, giving companies a way to scale their technical capacity quickly without going through a full recruitment cycle each time.

Why Traditional Hiring Struggles to Keep Pace

Permanent hiring makes sense for long-term, ongoing roles. But it becomes a genuine bottleneck when:

  • A project needs specialised skills the internal team doesn’t have
  • Work needs to start faster than a full recruitment cycle allows
  • Demand for technical work fluctuates rather than staying constant
  • A company wants to test a new capability before committing to permanent headcount

In these situations, waiting months to fill a role isn’t just inconvenient, it can mean missed deadlines, delayed launches, or lost opportunities altogether.

What Does Scaling a Tech Team Through Staffing Solutions Actually Look Like?

At a practical level, this approach means bringing in talented, technical resources to fulfil both short-term and long-term IT staffing needs, working as an extension of a company’s existing team rather than a separate, disconnected unit. This works particularly well for companies looking to scale up project requirements quickly, or those wanting to strengthen their core team with experienced IT professionals without a lengthy hiring process.

A client-centric team structure helps speed up development and keeps projects moving toward their deadlines, with the broader objective of helping a company function seamlessly even as its technical needs shift.

Practical Advantages of This Approach

Scaling a tech team this way tends to deliver a specific set of practical benefits:

  • Faster access to talent, avoiding the lengthy timelines of traditional recruitment.
  • Lower development costs, compared to the overhead of permanent hiring for short-term needs.
  • Fewer legal and administrative complications, since staffing arrangements typically involve less contractual complexity than direct employment.
  • Ability to overcome geographical limitations, accessing skilled professionals regardless of location.
  • Greater flexibility, scaling a team up or down as project needs evolve

Together, these advantages give companies a genuine edge in moving projects forward without the friction that traditional hiring can introduce.

Why Domain Expertise Matters, Especially in BFSI

Not all technical staffing needs are the same. Companies operating in specialised sectors, banking, insurance, asset management, benefit significantly from staffing resources who already understand the domain, rather than needing to be trained from scratch.

Experience working with banks, asset management companies, NBFCs, insurance companies, and broking firms brings a different kind of value than generic technical staffing. Resources with hands-on skills across large-sized databases, Microsoft technologies, life and general insurance, pension schemes, Mutual Fund Software, Wealth Management Software, demat operations, and analytics reporting can integrate into a project far more quickly, since they already understand the operational context they’re working within.

How Does the Engagement Model Actually Work?

A common question companies have is how billing and project structure work under this kind of arrangement. A Time & Material contract model is typically used, where teams work closely with the client to build an efficient project plan delivered across smaller timelines. This promotes flexibility, spreads the workload appropriately, and helps balance resources across the project.

Under this model, the client is billed for actual time spent on development, and plays a more active role in shaping the project’s direction compared to a fixed-price arrangement. This structure suits situations where requirements may evolve, since it allows the project plan to adapt without renegotiating a fixed scope each time.

Situations Where This Approach Tends to Fit Best

A few recurring scenarios tend to show up across companies that scale their tech teams this way. A project often has a defined scope but a tight timeline, leaving little room for a months-long hiring process. Sometimes the need is for a specific technical or domain skill that’s only required for the duration of one project, not a permanent addition to the team. Other times, a company is testing a new technology direction and isn’t ready to commit to full-time hires until the initiative proves itself. And fairly often, it’s simply a matter of an existing team being stretched thin, needing extra hands without adding long-term headcount.

Conclusion

Scaling a technical team quickly is often less about finding more people and more about finding the right people, with the right skills, on a timeline that actually matches business needs. IT staffing solutions offer companies a practical way to close this gap, combining faster access to talent, domain-specific expertise, and flexible engagement models that adapt as project requirements evolve. For companies facing tight deadlines or specialised skill gaps, this approach offers a considerably faster path forward than traditional hiring alone.

FAQs

1. What’s the difference between IT staffing solutions and traditional hiring?

Traditional hiring involves a full recruitment cycle for permanent roles, while staffing solutions provide access to skilled technical resources faster, for both short-term and long-term needs, without the same hiring overhead.

2. How does billing typically work under this model?

Most engagements use a Time & Material contract, where companies are billed for actual time spent on development, offering more flexibility than a fixed-price project structure.

3. Is this approach only useful for short-term projects?

No, it works for both short-term and long-term staffing needs, depending on whether a company needs temporary support or wants to strengthen its core team over a longer period.

4. Why does domain expertise matter when scaling a tech team this way?

Resources with prior experience in sectors like banking, insurance, or wealth management can integrate into a project faster, since they already understand the operational context rather than needing extensive onboarding.

5. Can a company scale the team back down once a project ends?

Yes, one of the core advantages of this approach is flexibility, teams can be scaled up during high-demand periods and scaled back down once the workload normalises.

© 2026 Winsoft Technologies India Pvt. Ltd.